
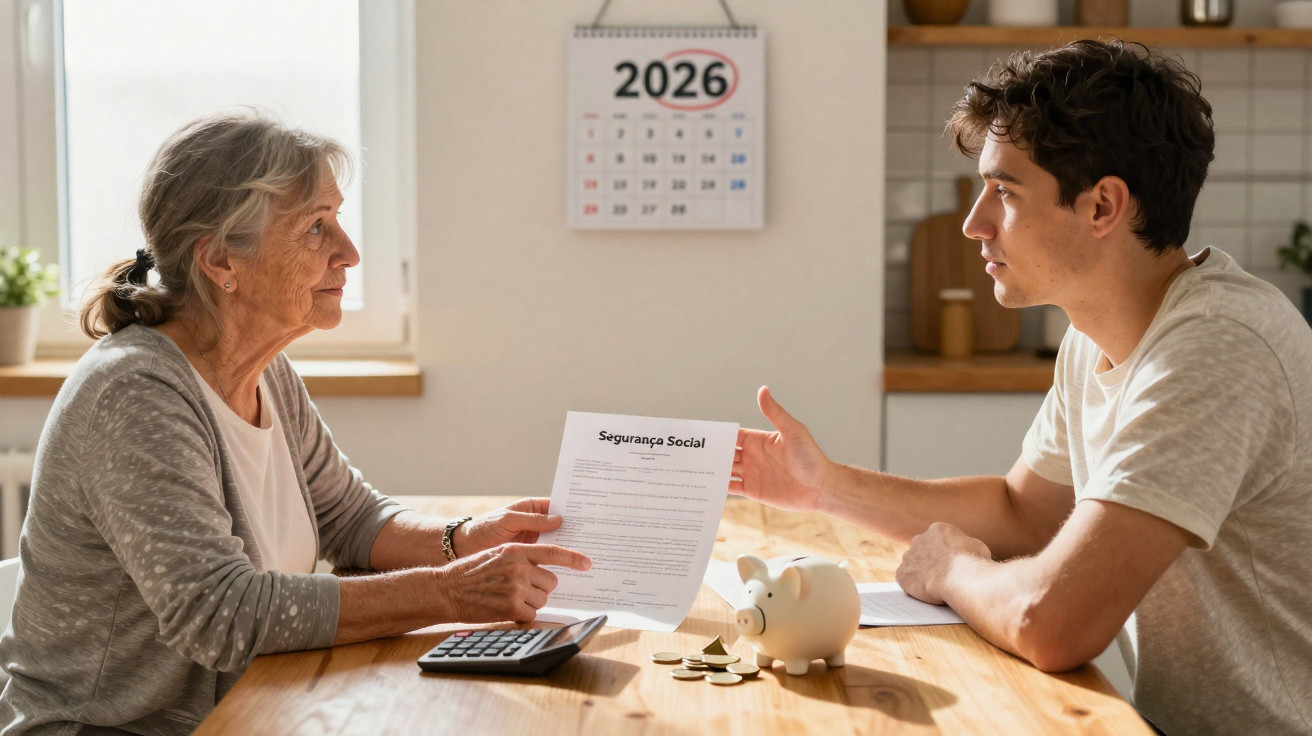
On a grey Tuesday at the Social Security office in Dayton, Ohio, the waiting area had the uneasy atmosphere of a family row that nobody wanted to begin. A retired factory worker gripped his ticket and murmured that he’d “paid in for 40 years.” Nearby, a young nurse scrolling through her phone exhaled sharply at a headline about “2026 Social Security changes.” For a moment, they looked at one another: both were tied to the same system, though clearly not to the same bargain.
Outside, a mother in her thirties pushed a pram past a poster that promised “benefits you can count on.” She looked at the sign and gave a quiet laugh.
The revised payment rules expected in 2026 are meant to preserve the programme.
They could also turn that unspoken strain into a public fight over money.
Why 2026 feels like a breaking point
Mention Social Security in a café where retired people meet, and the mood can shift almost immediately. To those already receiving payments, the monthly deposit is not an abstract programme or an entry in the federal budget. It pays for food, housing, medicine and fuel for visiting grandchildren.
The proposed 2026 changes put pressure on that already fragile confidence. Policymakers face bleak forecasts and are focused on three main choices: the amount today’s retirees receive, the amount workers contribute, and the age at which later generations can retire. Every choice places the burden somewhere else.
That is how a grandfather and granddaughter can find themselves quietly taking opposite positions on a spreadsheet.
Consider the figures people keep discussing in low voices. For years, the Social Security Trustees have cautioned that, by the middle of the 2030s, the main trust fund may be able to pay only around 75–80% of promised benefits. The year 2026 is not the precipice, but it is the turn in the road where the safety barriers begin to shift.
Ideas being considered for 2026 therefore include a different method of calculating benefits for higher earners, adjustments to cost-of-living increases, a higher payroll-tax cap and another rise in the full retirement age. These measures stop feeling “technical” when every dollar matters.
Speak to a 68-year-old widower who has just fixed his benefit amount and he may say: “Don’t you dare touch my check.” Ask his 32-year-old son, and the reply may be: “I’ll be lucky if anything is left.”
What makes 2026 particularly fraught is the quiet pledge on which the programme was founded: each generation finances the one before it, trusting that the following generation will do likewise. That arrangement is now unsteady.
Today’s retirees believe they have already met their obligation, having contributed throughout their working lives under one set of rules. Younger workers see those rules continually moving beyond their reach, with every “solution” asking them to pay more for less.
That is the heart of this acrimonious dispute over money. It is not merely about payments and statistics; it is about whose sacrifice is treated with respect, and who is left feeling deceived.
Preparing for 2026 Social Security changes without blaming each other
For anyone approaching retirement, one straightforward practical step is to calculate the figures using several possible 2026 outcomes rather than relying only on current rules. Use Social Security Administration online calculators, then test “what if” options: claiming at 62, 67 or 70, with and without potential changes to cost-of-living increases or higher taxation of benefits.
It may look dull on a page, but it can change the discussion around the kitchen table. Rather than arguing about imprecise worries, families can identify the real monthly effect if the rules become tighter or taxes increase.
The important thing is to view 2026 as a date for planning, not a date of catastrophe: a point at which to check the map again.
Many people take the opposite approach. They delay, avoid the subject and hope Congress will “figures it out.” Then a rule changes, and a brother who claimed early can feel short-changed beside a sister who waited and received a better outcome under a revised formula.
If you are still employed, this means creating a retirement back-up plan that does not cast Social Security as the hero of the story. A 401(k), IRA or HSA for future healthcare costs can all help; even modest regular contributions provide flexibility. Honestly, nobody manages this every day without fail. Yet every automatic transfer arranged now is one disagreement you may avoid later.
For retirees who already receive benefits, the approach is different: reduce the uncertainty. Ask questions, ask them again, and retain records of every letter and adjustment.
“Social Security was supposed to be the one thing we didn’t fight about in this country,” a financial counselor in Arizona told me. “Now I see parents and kids blaming each other for policy decisions neither of them made.”
- Discuss figures rather than blame. Instead of saying, “your generation ruined this,” ask: “What’s your projected benefit under the 2026 rules?” Then share your own projection. Look at the SSA statement together.
- Share responsibility for solutions. Grandparents can pass on budgeting methods and experience of living frugally. Adult children can help investigate extra income, savings apps or part-time work options.
- Set one joint aim. It might be “no one in this family skips meds because of money” or “we avoid taking on high-interest debt.” A shared goal moves attention away from generational blame and towards getting through it.
The unspoken question beneath the money fight
When people discuss 2026 Social Security changes, they seldom voice their deepest fear. Retirees worry about being labelled a burden. Younger workers fear they will support everyone else and still be left with nothing.
Behind every policy chart is a simple truth: this argument concerns dignity as much as it concerns dollars.
The programme was never an individual savings account; it was a social contract extending across generations. That contract is now being renegotiated live: on cable-news panels, in congressional offices and at kitchen tables where the fridge seems to hum slightly louder in the silence.
| Key point | Detail | Value for the reader |
|---|---|---|
| 2026 as a pivot year | Rule changes and proposals are intended to slow the trust-fund shortfall, potentially moving costs between current retirees and future workers. | Helps you regard 2026 as a prompt to revisit your retirement strategy, rather than a cliff edge. |
| Different stakes by generation | Retirees seek to protect existing benefits; younger workers anticipate higher taxes and later retirement in exchange for possibly smaller payments. | Explains why discussions can feel strained and how not to take that tension personally. |
| Family-level planning | Testing several benefit scenarios, speaking openly and building additional savings can reduce reliance on any single rule. | Offers practical ways to adapt, whichever version of 2026 ultimately arrives. |
FAQ
Question 1: Will my Social Security check be cut in 2026?
No official across-the-board reductions are currently scheduled specifically for 2026. The proposals under consideration involve changes to formulas, eligibility and taxation intended to keep the system solvent beyond the 2030s. However, if you plan to retire around that period, prepare for the possibility of slower benefit growth or higher taxes on benefits.
Question 2: Are current retirees protected from every change?
Political realities make major reductions for existing retirees unlikely, though not impossible. Legislators generally try to “grandfather” people already receiving benefits or apply less severe changes to them. Even so, cost-of-living formulas and the taxation of benefits can be altered for everyone, including people who have already retired.
Question 3: Will younger generations receive Social Security at all?
The strongest projections indicate that the programme will continue, but that without changes it may pay only about three-quarters of promised benefits once the main trust fund is depleted. This is why 2026 and the surrounding years carry so much tension: the sooner reforms are made, the smaller the shock for future retirees.
Question 4: Should I claim benefits early before the rules change?
Claiming early solely from fear may backfire. Taking benefits at 62 fixes a permanently lower payment. For many people, particularly those in reasonably good health who can continue working, waiting until nearer full retirement age or even 70 may provide stronger protection than rushing to claim ahead of possible changes.
Question 5: What is one thing I can do this year about the 2026 changes?
Print your latest Social Security statement and review it with someone you trust, whether that is a spouse, adult child or friend. Then model at least one alternative: “What if my benefit grows slower?” or “What if I work two extra years?” The figures may not be attractive, but that conversation is where genuine control begins.
Comments
No comments yet. Be the first to comment!
Leave a Comment