
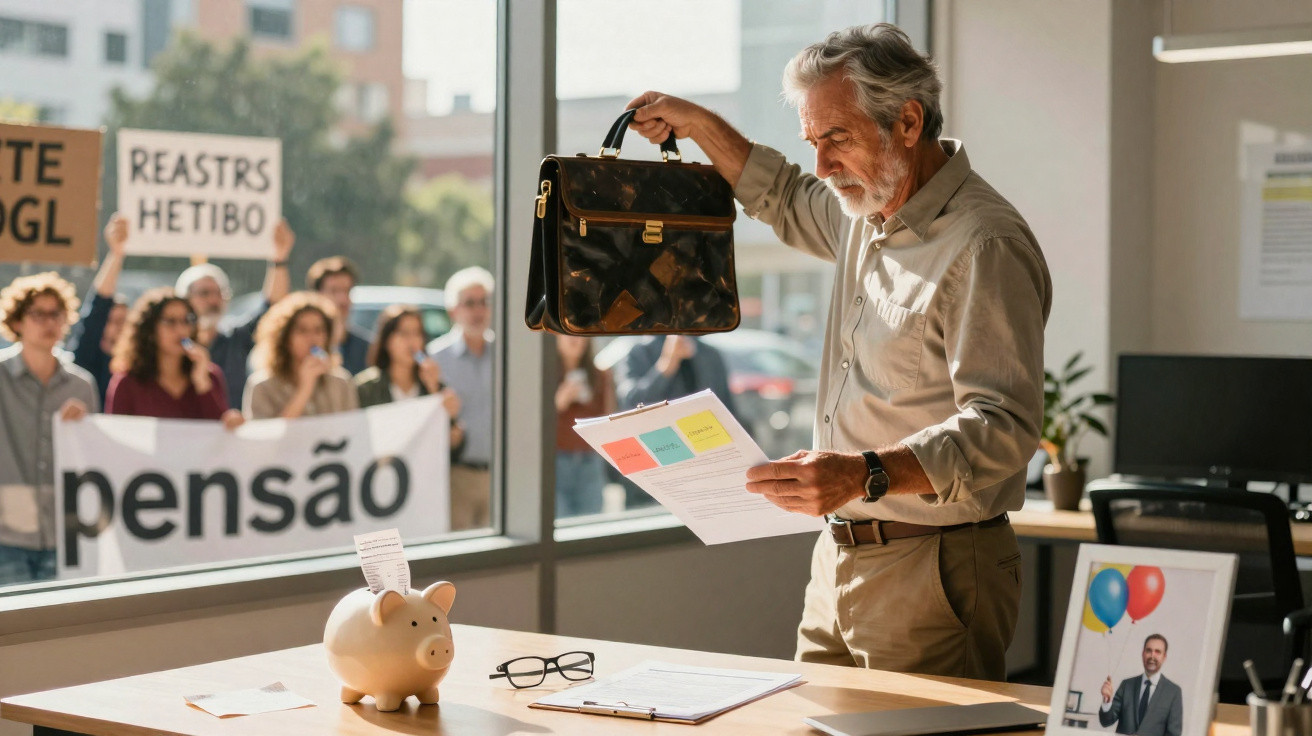
On a wet Tuesday morning in Frankfurt, Lukas, a grey-haired accountant, looked at the headline glowing on his phone: “Raise retirement age to 75, say leading economists.” He laughed aloud on the tram, before noticing that no one around him shared the reaction. Opposite him, a woman of perhaps 62 clutched her reusable shopping bag more tightly. A young barista in a worn hoodie read the same story, his eyebrows lifting before vanishing under his fringe. For a moment, the tram became a silent mini focus group, with everyone seemingly thinking: “Wait… 75?”
Phones lit up, online comment threads erupted and television programmes rushed to book guests. To some, the proposal was realism; to others, it was theft. Beneath the startling headline sits a stark calculation, built from spreadsheets and demographic trends.
The trouble is that this calculation is lived out in people’s bodies.
Why economists now discuss 75 as the new 65
The economists’ central case is starkly simple: if people live longer, pensions must cover more years, and financing them requires people to remain in work for longer. They point to charts in which life expectancy rises like a mountain incline while birth rates plunge like a sinkhole. In their view, the figures no longer add up. There are fewer younger workers, more pensioners and increasingly strained public finances in countries already weighed down by public debt.
Seen from that angle, 75 is not intended as a provocation but as a turning point. Raise the retirement age, they argue, and the system can breathe again.
The so-called “new old age” can be seen in the corridors of any large-city hospital. There are 70-year-olds running 10 km races, grandparents attending Pilates classes and retired teachers travelling internationally with discounted rail passes. Statistically, many people now reach 80 or 90, often enjoying several comparatively healthy years after 65. That is the evidence economists are keen to put on their PowerPoint slides.
But elsewhere in the same city, a 61-year-old supermarket cashier is privately counting down her shifts as standing becomes more painful every day. A 58-year-old construction worker masks shoulder pain with humour. Suggesting that they should continue until 75 changes the mood of the discussion very quickly. Charts of life expectancy do not reveal damaged backs or worn knees.
The conflict comes from two valid realities meeting head-on. In theory, pension systems are strained by demographics: fewer people paying in, more people drawing benefits and substantial deficits ahead. In reality, jobs do not place the same demands on ageing bodies, and people do not all enjoy equally long or healthy lives. Economists maintain that, without later retirements, future pensions will be reduced or collapse entirely. Trade unions and social workers respond that applying a universal age of 75 overlooks inequality, treating a software engineer and a night-shift cleaner as though they had the same body, lived in the same area and faced the same opportunities.
This is the point at which a question of public budgets becomes a question of fairness.
How to respond if retirement at 75 becomes reality
Every major national reform creates a smaller, personal concern: “So what does this change for me?” One understated but effective response is to view a working life as a long journey rather than a straight motorway. Even in your 40s or early 50s, that may mean asking: “Could I be doing this exact job at 70?” When the answer is clearly no, the issue is no longer philosophical; it is practical. Retraining. Additional skills. A fallback plan.
Some employees are beginning to create a gentler transition in their careers. They move from full-time work to part-time hours, or switch from physically strenuous posts into mentoring, administration or remote work. It is neither simple nor available to everyone, but such modest changes can make the difference between coping and breaking down.
There is a financial element too. No one enjoys being told to save for decades. Honestly, nobody manages it perfectly every single day. Yet when retirement seems like a moving target, having a personal financial cushion becomes less a luxury than a means of survival. This might involve extra payments into a private pension, a modest investment account or simply clearing debt more quickly.
There is also an emotional pitfall. On hearing “75”, some people disengage and say to themselves, “What’s the point, they’ll just push it again.” That resignation helps nobody. You do not need a flawless financial plan; you need one that is slightly better than the one you had last year.
While economists produce dense reports, people in their 50s raise different concerns quietly over family meals: “Will I still have a job at 67? At 70?” One evening in Paris, a social policy expert put it to me this way:
“Raising the retirement age is intellectually easy and politically explosive. The real courage would be to admit that not everyone can or should work to the same age, and design the system around that messy truth.”
Within that messy reality, several practical steps appear repeatedly:
- Check your pension record annually rather than only once in your life.
- Speak to your employer about internal moves well before your body leaves you with no choice.
- Keep records of health problems connected to your work, for any future claim or negotiation.
- Discuss a “Plan B” openly with your partner or family in case the rules change again.
- Remain modestly employable by building one new skill, learning one new tool and making one new contact at a time.
The question beneath retirement age 75: what sort of old age do we want?
Remove the technical language and the argument over 75 touches something deeply personal: what is owed to people after a lifetime of employment? Not merely as voters, but as neighbours, children of ageing parents and future older people ourselves. Most of us know the feeling of seeing a 69-year-old colleague rubbing their wrists after a long shift and quietly thinking, “They should be resting now.” At the same time, many older people say work keeps them socially and mentally alive, provided they have the choice.
A simple truth lies beneath the noise: pensions are not just about money, they are about dignity and time. Time for grandchildren. Time to recover after decades governed by alarms and deadlines. Time that is not continually measured by productivity.
If 75 becomes the next political benchmark, societies must choose between merely lengthening working lives and fundamentally redesigning them. Flexible departures from work, earlier retirement for demanding occupations, partial pensions and new kinds of community work may sound complex, until the alternative is considered. That alternative is a legal line which effectively says, “good luck until 75, everyone.”
Public anger at this proposal is genuine, just as the financial precipice described by economists is genuine. Between those two cliffs is a narrow route on which citizens call for transparency, nuance and shared sacrifices that do not repeatedly land on the same shoulders. It begins with a question we can all voice, not only to economists but to our own governments:
If we’re going to work longer, what are you willing to change so we can actually live longer, too?
| Key point | Detail | Value for the reader |
|---|---|---|
| Raising age to 75 is driven by demographics | Longer lives and fewer younger workers put pressure on pay-as-you-go pension systems | Helps explain why this debate keeps returning to the news |
| Not all workers can last to 75 | Physically demanding, lower-paid jobs wear down bodies faster than office work | Provides arguments for challenging one-size-fits-all reforms |
| Personal planning softens sudden reforms | Career changes, savings buffers and health records can provide some protection | Transforms an alarming political issue into practical action you can take |
FAQ:
- Question 1 Why are economists specifically talking about 75 and not, say, 68 or 70?
- Question 2 Does raising the retirement age automatically mean I’ll have to work until that age?
- Question 3 What happens to people in physically demanding jobs under such a reform?
- Question 4 Can private savings really compensate for later public pensions?
- Question 5 What concrete steps can I take now if I’m in my 40s or 50s?
Comments
No comments yet. Be the first to comment!
Leave a Comment