
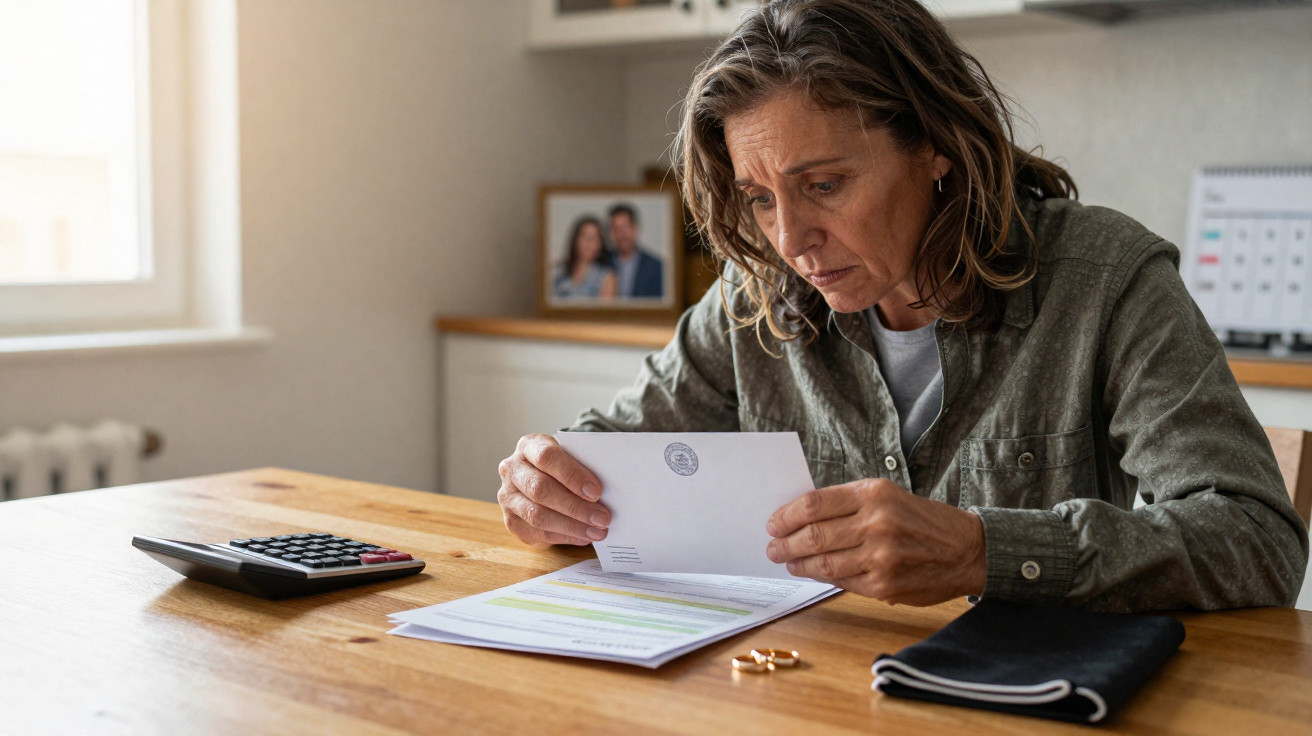
On a grey February morning, in a small notary’s office behind the tax building, a woman in her early sixties studies a pile of documents she does not understand. Her husband died three months earlier. She still sleeps on his side of the bed. She had expected to sign “a few forms” and, at last, begin moving forward.
Instead, she finds herself in a cold legal maze: dense clauses, cross-references and a new law she had never even heard about. The notary clears his throat, straightens his glasses and quietly explains that the tax rules have changed. The house, their savings and everything they had built during forty years together suddenly seem far less simple than they once believed.
The most unsettling part? Nobody told her.
When a February law quietly changes the rules of grief
Each year, thousands of couples go to sleep believing that, should anything happen, “everything will go to my spouse”. It seems self-evident, almost instinctive. You share a life, a mortgage and a Netflix account. Naturally, you assume you share the future of your assets too.
Then a low-profile law, passed in February and buried beneath technical language, alters a few lines of the tax code. There is no dramatic announcement, no major television debate and no outraged front pages. Yet it subtly changes the way inheritances are assessed and taxed, particularly where the surviving spouse is not fully protected by a marriage contract or a will.
Officially, nobody is “taking” your money. In reality, the tax office gains more power and your spouse may be less protected than you assume.
Consider Marc and Elise, an entirely ordinary couple in their fifties. They are married without a particular contract and have two adult children. Marc dies suddenly from a heart attack. They own a modest house, some savings and life insurance; nothing extravagant. Elise assumes she will “inherit everything” and settle matters with the children later, perhaps over Sunday lunch.
At the notary’s desk, the picture is different. New valuation rules, stricter deadlines, reclassified assets and tax options quietly amended since that February law mean the tax burden rises like a silent tide. She must rapidly select from several inheritance arrangements she has never encountered. One choice protects the children; another favours the tax office; a third gives her some protection. None delivers what she believed she already had.
Eventually, she keeps the house but must sell an investment flat that the couple had intended to rely on in retirement, simply to meet the bill.
What happened to Elise is not an obscure legal ambush. It follows logically from a system that has progressively shifted the balance towards the Treasury in the name of “harmonization” and “modernization”. When tax law changes, the press release rarely identifies those who stand to lose.
Over the years, exemptions are restricted, allowances remain frozen as house prices increase, and the valuation of assets is revised. Then the February law arrives without much publicity and tightens a few more screws. It is not drastic, but it can push many estates further into taxable territory, particularly where property prices have risen.
Some inheritance specialists call this invisible confiscation: nobody arrives to take your house, but a portion of what you expected your spouse to receive disappears into state coffers before your grief has even begun to settle.
How to fight back: small gestures that change everything
You do not have to find yourself one day before a notary, learning that a discreet February law has altered your future. It does not require you to become a tax specialist. It simply means doing, early and without panic, what many couples keep putting off: spending an hour establishing what would genuinely happen if one of you died tomorrow.
One useful approach is almost childishly straightforward. On a sheet of paper, make three columns: “What we own”, “Who owns it now”, “Who would get it if I die first”. Take that page to a notary or estate adviser and ask one direct question: “Where would taxes bite, exactly?”
That single exercise often shows that what you saw as your spouse’s safety net is, in fact, a net for the tax office.
We have all had that thought: we will “sort out paperwork later”. There is always something more appealing to do on a Saturday than discuss death and tax bands. Frankly, nobody wants to deal with it every day.
The danger is that the law does not wait until you feel prepared. It changes in the middle of winter, in parliamentary corridors, through wording deliberately made to sound dull, and suddenly the default rule no longer benefits your partner as you expected. Those who delay making a will, changing their matrimonial property regime or simply naming beneficiaries on a life insurance policy may be handing over control of their assets without realising it.
For the surviving spouse, the feeling is often a blend of bereavement and betrayal: “Why did no one tell us?” The harsh answer is that the system relies on your silence.
“On paper, spouses are protected,” sighs a Paris notary I spoke with. “But each new fiscal tweak takes a little more room away from them, and almost nobody notices. The state doesn’t need to expropriate. It just raises the price of mourning.”
- Update beneficiary clauses on life insurance, pensions and savings plans every 3–5 years, particularly following a marriage, divorce or birth.
- Ask your notary to model your estate as if you died tomorrow, applying the current law and using actual figures and actual tax.
- Think about a bespoke marriage contract or a donation between spouses to strengthen the survivor’s share, rather than depending solely on the legal default.
- Draw up a brief, unambiguous will, even if you feel “everything is obvious”, and store a copy somewhere your spouse can locate promptly.
- Discuss money and death with your partner at least once, before illness or age makes those conversations emotionally charged and hurried.
A new social fracture: those who know, and those who discover
Behind this February law and earlier tax adjustments lies a troubling divide in society. On one side are families supported by solicitors, notaries and wealth managers, who adjust quickly whenever a new measure appears. On the other is the overwhelming majority, who learn too late that the ground rules have shifted.
Those who are “in the know” reorganise their assets, distribute property during their lifetime and use optimised life insurance and usufruct arrangements. Everyone else depends on common sense and imprecise assumptions: “The surviving spouse is protected”, “The children will sort it out”, “We do not have much anyway”. These beliefs are reassuring, but they are also becoming increasingly out of date.
The law no longer forgives naivety. The divide between people who can protect their partner and those who watch a third of their efforts disappear in tax is quietly widening, like a fracture beneath a freshly painted wall.
The more the state tightens its tax grip on inheritances, the more it drives families towards earlier, more strategic transfers. Give while you are alive rather than after death. Pass bare ownership to children while retaining the usufruct. Use life insurance to direct capital to your spouse while reducing tax for the children later.
Most people do none of this because nobody has explained it to them without jargon. They encounter terms such as “full ownership”, “usufruct”, “reserve heirs” and new calculation methods at the worst possible moment: just after someone they love has died. Those who have had the instinct to consult a professional, even once, are playing in a different league. The law is identical for everyone, but its effects are profoundly unequal.
That is the quiet unfairness of these February changes: officially neutral, yet in practice regressive for the disorganised and exhausted.
Put plainly, some recent changes mean that, for many married couples, the tax office has become a kind of silent third heir: absent from family photographs, but taking a very real share. This is not because the state is deliberately cruel, but because balancing public finances often relies on technical measures that nobody understands until it is too late.
There is a bitter irony in this. Politicians repeatedly say that the family is “the foundation of society”. Yet, at the same time, the inheritance framework forces that foundation to become more legalistic and more contractual, fighting for what was once assumed: that the spouse comes first.
Between the lines of that February law and those that preceded it, a different message emerges: love does not protect your partner in the eyes of the tax code. Paper does.
Opening our eyes before the envelope from the tax office arrives
Once you understand that one line in an obscure February law can redirect part of a lifetime’s work away from your spouse, you cannot overlook it again. You begin to view differently the forms signed without reading, the insurer emails you archive and the annual pension-fund letters that seem too complicated to tackle.
Discussing death with the person with whom you share your life is not romantic. It may feel awkward, even harsh. But assuming that the law will naturally support you when the time comes offers only fragile reassurance. The meaningful act of protection today is not a grand declaration about “forever”. It is a meeting with a notary, a coffee between two signatures and a few words in black ink saying: “If I go first, this is what I want for you.”
In a world where the tax office moves forward silently, line by line, clarity is the only genuine defence. And it must begin before bereavement, not afterwards.
| Key point | Detail | Value for the reader |
|---|---|---|
| February law shifts the tax balance | Discreet tax adjustments increase the potential tax share on inheritances, especially where no specific spousal protections are in place. | Helps readers understand that “default” legal rules may no longer protect their partner in the way they expect. |
| Preparation beats discovery | Straightforward measures - asset mapping, simulations, updated beneficiary clauses and wills - can counter some of this invisible confiscation. | Provides practical ways to protect a surviving spouse from unexpected tax pressure at the worst possible time. |
| Advice creates a new inequality | Families receiving legal and tax advice adapt quickly, whereas others only discover the consequences after a death. | Encourages readers to join the “informed” group through one or two focused professional consultations. |
FAQ:
- Question 1 Does this February law mean the state can “take” my spouse’s inheritance?
- Answer 1 No one comes to seize your assets directly. The change affects how the estate is assessed and taxed, which may reduce the amount that ultimately reaches your spouse.
- Question 2 We are married without a contract. Is that enough to protect the survivor?
- Answer 2 Not always. The default regime provides some protection, but its practical effect depends on your assets and children. A donation between spouses or a will may significantly improve the survivor’s position.
- Question 3 We do not have much, so do we really need to worry about this?
- Answer 3 Even relatively modest estates can be destabilised by tax and valuation rules, particularly where most of the wealth is tied up in a home the surviving spouse wishes to retain.
- Question 4 What is the first practical step to take tomorrow?
- Answer 4 List your assets in three columns (what, who owns, who would get it) and take that sheet to a notary so they can model your estate under current law.
- Question 5 Is life insurance still a good way to protect a spouse from tax?
- Answer 5 Often it is, provided beneficiary clauses are current and suited to your family circumstances and age. A professional can check whether your policies still match the latest rules.
Comments
No comments yet. Be the first to comment!
Leave a Comment