
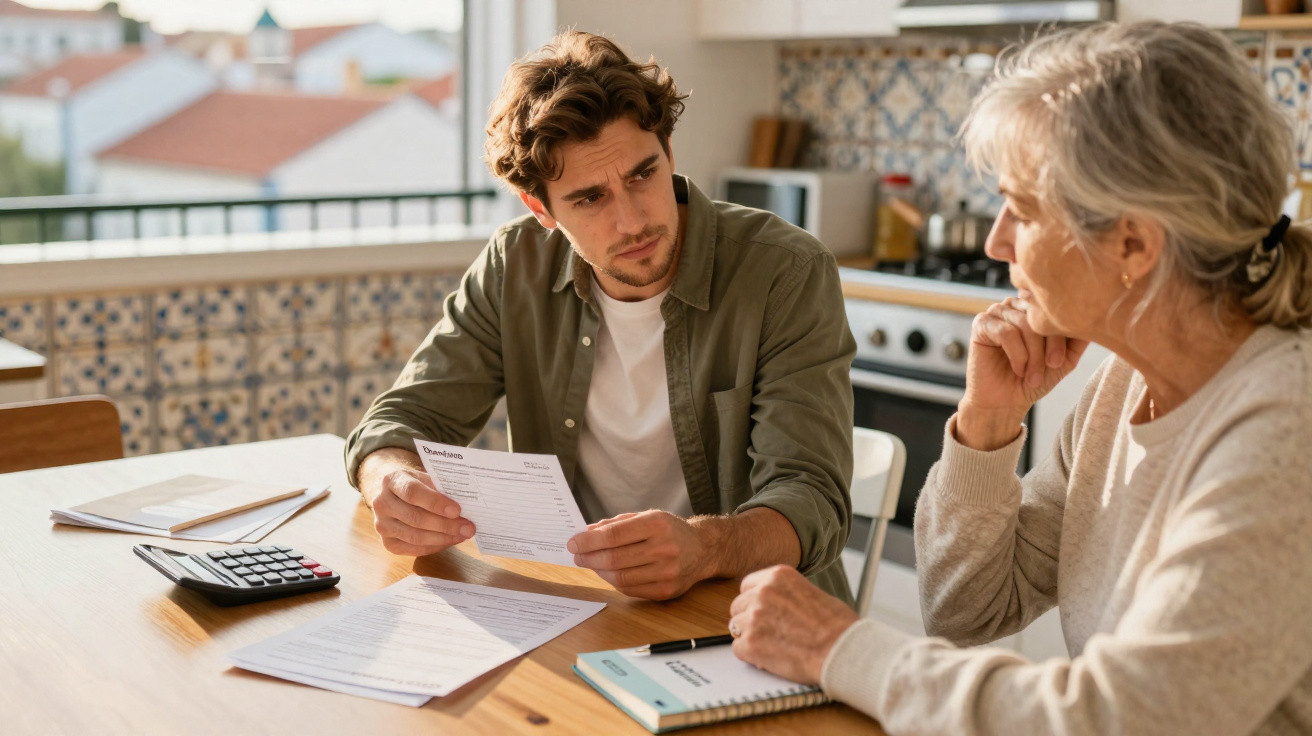
It was m., just as the first coffee began dripping into the mug. “Tax update for 2025 – action required.” At one end of the kitchen table, a 32-year-old marketing manager read the message on her phone, with rent and increasingly expensive food already on her mind. At the other, her retired father flicked through the morning headlines on his tablet, quietly relieved to find “pension protections” trending once more.
One home, two generations and a tax system that appears to favour one far more than the other.
She scanned the details: increased withholding, fewer allowable deductions and higher social contributions. He saw another headline: “Retirees shielded from new tax hikes in 2025.” They looked at one another, each reluctant to voice the obvious.
Her payslip was about to become smaller. His monthly income would not change by a penny.
The quiet between them seemed to be about more than money.
The strange new social contract: retirees safe, workers squeezed
Throughout much of the Western world, 2025 is beginning to resemble a subdued tax earthquake. Governments speak of “stability” and “protecting purchasing power for seniors”, but the burden is falling on those who still have to set an alarm for work. Pension tax bands remain favourable, particular exemptions are being extended, and new tax credits are aimed at retirees – including affluent ones.
Meanwhile, people in work are facing steeper social charges, vanishing deductions and a gradual, almost imperceptible decline in their take-home pay. This is not a sudden shock. It is happening bit by bit, which is precisely why it feels so unsettling.
In theory, the arrangement seems reasonable: support people who have paid in throughout their lives. But in real kitchens, small flats and open-plan workplaces, it can look rather different. It feels like the terms of the deal are changing before our eyes.
Consider Germany, where analysts anticipate another rise in the effective tax burden on wages in 2025, while generous allowances for certain pension income remain in place. In the UK, frozen tax thresholds are drawing more employees into higher bands, while many retirees gain from triple-lock increases to the state pension that remain lightly taxed.
In the United States, 2025 forecasts point to a modest increase in payroll-tax pressure for middle-income employees, while substantial parts of Social Security and some retirement income continue to receive partial protection, particularly below the upper thresholds. The same pattern appears again: employment income is taxed more heavily than passive or pension income.
Speak with people in their 20s, 30s and 40s, and a familiar combination of resignation and restrained frustration emerges. They are contributing more, being urged to save more, and yet are living with a system that still seems designed around older voters whose income is treated by the state as fragile. On buses, in pubs and in Slack channels, one question keeps returning: who, exactly, is funding all of this?
There is an unforgiving demographic rationale behind the change. Developed countries are ageing quickly, with more retirees and fewer workers. Healthcare spending is climbing, and pension provision is costly to sustain. Politicians understand that older people vote more consistently, while any suggestion of reducing their net income can prove explosive at the ballot box. Rather than confronting retirees directly, governments often opt for the less visible approach: payroll adjustments, frozen thresholds and subtle measures that gradually reduce workers’ take-home pay.
Economists describe this as an intergenerational transfer. Workers tend to use different language. The narrative that “we must protect seniors” is real and human, but it conceals a compromise: that protection has to be funded somehow. More often than not, it comes from those who are still commuting, repaying mortgages and putting money aside for a retirement that may not receive the same protection as the one they are financing today.
How workers can fight back without burning out
There is no miraculous tax trick that will make 2025 painless. However, one change in perspective can make a difference: look beyond salary alone and focus on “after-tax leverage”. In practice, that means viewing every euro or dollar as part of a system that can, to a degree, be reorganised. Pay is only one source of income. Additional earnings, benefits, deductions and the way savings are held all affect what the tax authorities ultimately assess.
In many countries, the specific response is remarkably consistent: place more of your financial life in tax-advantaged areas. Employer pension schemes, individual retirement accounts, health savings arrangements and long-term investment wrappers can all help. They will not eliminate the impact of higher payroll taxes, but they can reduce the drain on your overall net worth.
That may sound dull beside angry headlines about unfairness. Yet quiet power is often found in the duller choices.
Practically speaking, begin by reviewing your payslip and latest tax return. Exactly where is your money going? Social contributions, income tax or local charges? Identify the two largest items, then examine the most obvious options: could you raise pre-tax pension contributions? Could some of a cash bonus be exchanged for a benefit subject to gentler taxation? Could part of your savings move from an ordinary account into a tax-deferred arrangement?
Many employees are already making modest, intelligent decisions that never reach the headlines. A nurse in Lyon uses a small employer savings plan to shelter some overtime pay. A software engineer in Austin contributes up to the maximum level in his 401(k), simply to reduce his taxable income enough to avoid the next federal band. A freelancer in London arranges her work so that part of her income passes through a company and is therefore covered by different rules.
None of them is “gaming the system.” They are simply studying the rules as closely as the system studies their payslip.
Many workers falter when frustration becomes an emotional spiral. Seeing retirees protected can easily lead to resentment, followed by inaction. Inaction means leaving the tax letter unopened, not renegotiating a contract and never reviewing a contribution rate. Over the next decade, doing nothing can quietly make the problem larger.
There is also a more personal source of strain: adult children see their parents receiving stable, lightly taxed income while they themselves manage higher childcare bills, rising rents and greater deductions. Nobody wants a family meal to become a budget meeting. Still, money can occupy the room like a third person at the table.
Let us be honest: nobody really does all of this every day.
The people who do manage to get ahead usually take one uncomfortable step each year: renegotiating a single clause, opening one new account or setting up one modest automatic transfer into something tax-efficient. Small actions can have an enormous long-term effect. Resentment does not alter the figures; one intentional adjustment can.
“Our tax system is a mirror,” says one public-finance researcher I spoke to. “When you see retirees shielded and workers squeezed, you’re not just seeing economics. You’re seeing who a society chooses to protect when things get tight.”
That reflection may be unpleasant, but it can also serve as a guide. It identifies where the strain is growing and where there is still space to breathe. For some people, that room comes through career decisions, such as moving from salaried employment to a mixed arrangement with freelance days taxed differently. For others, geography offers an option, with remote workers discreetly relocating to regions or countries where employment income is taxed more lightly.
At a more everyday level, several steps can lessen the impact of 2025’s tax changes:
- Review your tax withholding early in the year rather than waiting for an unwelcome surprise.
- Use any pension or savings scheme offered by your employer, even if you begin with a small contribution.
- Speak candidly with parents or older relatives about support working in both directions, rather than only one.
The system may seem skewed, but there are still areas in which your decisions have substantial influence.
A new kind of generational conversation about money
The events of 2025 are more than a minor tax adjustment. They will become part of a longer story about who benefited, who lost out and who said nothing. Some retirees feel uncomfortable about their relative protection. Others believe they “earned it” through decades of contributions. Many workers feel trapped in between, financing services they rarely use and benefits they doubt they will ever receive in the same form.
That strain need not become a lasting war between generations. It could instead lead to an uncomfortable but essential discussion: what are people genuinely prepared to share across age groups, and what should be renegotiated? In some families, parents may help adult children to build pension savings or a deposit, using their tax-favoured stability to reduce younger people’s exposure.
At a wider level, younger employees are beginning to respond in quieter and more strategic ways. Voting habits are changing. Trade-union demands now cover not only pay levels but also the tax-aware design of benefits. Smaller policy campaigns are concentrating on the fairness of labour income compared with pension income, instead of setting young and old against each other in abstract cultural disputes.
Most of us have experienced the moment of looking at a payslip or pension statement and feeling as though the system is looking back. The 2025 arrangement – retirees shielded, active workers paying the price – makes that encounter more intense. But it also raises another question: if this is the social contract being offered, what kind of contract do we actually want for ourselves, our parents and our children?
Some people will adapt quietly and optimise. Others will organise and demand reform. Others will simply carry on, because daily life already feels difficult enough. Somewhere in that mix lies the next version of how we share money across generations.
The kitchen-table moment from the start of this story is now playing out everywhere. Two screens, two lives and one set of rules that treats them very differently. Whether it feels like protection, betrayal or simply reality depends greatly on which side of the payslip you occupy – and what you choose to do with that feeling.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| Retirees shielded | Many 2025 tax changes maintain or extend protections for pension income | Understand why retirees’ incomes can appear untouchable |
| Workers squeezed | Payroll taxes and frozen thresholds increase the effective burden on wages | See exactly where and how your pay is being reduced |
| Room to act | Small, targeted actions (pre-tax savings, benefits, structure) can offset some of the pressure | Identify practical steps to reduce your actual tax bill |
FAQ:
Why are retirees protected from many 2025 tax hikes?
Ageing populations, high voter turnout among seniors and the political risk of touching pensions push governments to shield retirees, even when public finances are tight.Are all retirees really safe from higher taxes?
No. Low and middle-income retirees are often protected, but wealthier retirees can face changes on investment income, property taxes or inheritance rules.How exactly are workers paying the price?
Through higher social contributions, frozen tax thresholds that drag them into higher bands, and the gradual erosion of deductions tied to work and family.What can I do as an employee facing higher taxes in 2025?
Explore pre-tax retirement contributions, employer benefits with favourable tax treatment, and simple restructuring of savings into tax-advantaged accounts where available.Does this mean a generational conflict is inevitable?
Not necessarily. Families and societies can renegotiate support flows, with retirees using their protected income to help younger workers buffer the pressure and push together for fairer rules.
Comments
No comments yet. Be the first to comment!
Leave a Comment