
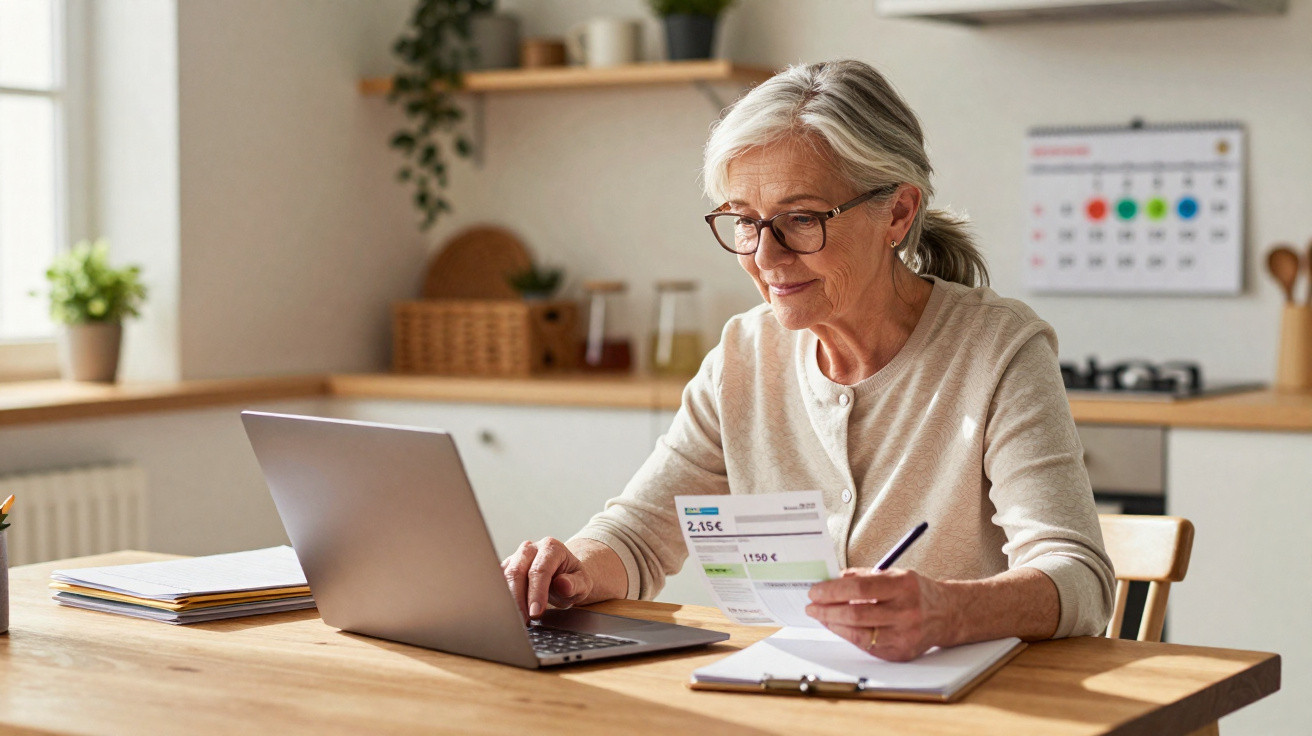
At 71, Mireille was not looking for a miracle. She simply wanted to top up a pension that had become too tight as rent, electricity and food shopping took up an outsized share of her budget. One Tuesday morning, while looking at her bank statement, she revisited an idea she had assumed was off limits: returning to paid work without losing her pension. A few months later, her childcare and administrative-support assignments were bringing in as much as €2,150 gross in some months. This was neither a secret pension nor concealed financial support. A lawful arrangement, widely misunderstood, had transformed her day-to-day life. That distinction matters enormously.
The €2,150 figure conceals a much simpler reality
What stands out in Mireille’s story is not just the amount involved. It is the fact that a pensioner can continue receiving their pension while earning a wage. The arrangement is known as combining employment and retirement: it allows someone who has claimed their retirement entitlements to take up salaried or self-employed work again, provided certain requirements are met. In her case, the €2,150 was not paid by Social Security on top of her pension. It was employment income earned for hours she had actually worked. That may sound less dramatic, but it is crucial in avoiding false expectations.
Mireille had spent almost 40 years working for a small transport company. When a former neighbour asked her to help with online paperwork and arranging medical appointments, she initially declined, convinced that her pension could be stopped. After getting in touch with her pension fund, she learned that she could return to work. Three families then entrusted her with a few hours each week. Her earnings varied between CESU declarations, homework help and supporting older people. During one especially busy month, she reached €2,150 gross.
The claim that “Social Security had tried to censor the information” is unsupported by any verifiable evidence. The rules on combining employment and retirement are public and are set out by L’Assurance retraite, supplementary pension funds and administrative information bodies. The real issue is more likely to be technical communication that is hard to follow for anyone who has never had to decipher a pension record. We all know the feeling of receiving an official letter that seems to be written in a foreign language, even though it directly affects our lives. What some pensioners experience as silence is often a lack of clear explanation rather than deliberate concealment.
How to return to work without putting your pension at risk
The first step is to check whether you qualify for the full employment-and-retirement combination arrangement. As a rule, you must have claimed all your retirement pensions, in France and abroad where applicable, and reached the legal retirement age with a full pension, or the age at which a full pension is granted automatically. Where these conditions are met, income from returning to work is not capped. Mireille had waited until she was 67 before claiming all her pensions, which made her case simpler. Before signing a contract or issuing an invoice, it is best to obtain written confirmation from your pension fund.
Many people mix up the full arrangement with the capped version. If not every condition is met, it may still be possible to work, but employment earnings must remain below a certain threshold. If that limit is exceeded, the pension may be reduced or suspended temporarily. Let us be honest: hardly anyone checks thresholds, effective dates and the relevant schemes every day. Yet an hour on the phone with L’Assurance retraite, or an appointment at an information point, can prevent months of adjustments and an unwelcome surprise in your bank account.
It is also important to distinguish between taking up work with a new employer and returning to a former employer, as the latter can involve a waiting period in some circumstances. The rules vary according to an individual’s employment history, retirement date and pension scheme.
“Combining employment and retirement makes it possible to continue or resume an activity while receiving a pension, provided the conditions applicable to the individual’s circumstances are met,” L’Assurance retraite states in information intended for policyholders.
Before getting started, three habits can make a real difference:
- request your individual pension situation statement;
- ask for written clarification of the type of arrangement that applies;
- retain contracts, payslips and correspondence with pension funds.
Combining employment and retirement: extra income, never an automatic promise
Mireille’s situation will resonate with many pensioners because it brings to mind a very practical worry: having to account for every expense from the middle of the month onwards. However, her €2,150 is neither guaranteed nor achievable by everyone. It depends on her available time, health, skills, the number of hours she can find and her employment status. Someone working ten hours a week on the minimum wage will plainly not receive the same amount as a pensioner carrying out specialist consultancy or secretarial assignments. “Legal” does not mean “automatic”.
Since 1 September 2023, the full employment-and-retirement combination arrangement may also generate new pension entitlements from contributions paid after returning to work, subject to certain limits. This development is worth knowing about, as it overturns the former belief that working after retirement never created any new rights. The second pension remains regulated and does not turn modest work into a windfall. However, it can make a difference for someone who returns to work for several years. The details need to be considered carefully according to the pension scheme involved.
The best option is not always the one that receives the most attention on social media. Some people may prefer a few declared hours of domestic cleaning, while others may choose tutoring, mediation, pet sitting or a craft activity they had previously given up. The aim is also to protect your pace of life. Working at 71 can provide structure, social contact and a sense of usefulness; it can also become exhausting if financial goals overwhelm everything else. Extra income should not come at the expense of peace of mind.
Above all, Mireille’s experience shows how an administrative rule can have very human effects when it is understood at the right time. Behind cold expressions such as “claiming entitlements”, “full pension” and “income ceiling” are pensioners hesitating over whether to accept an assignment, cover for a colleague or restart a former activity. Discussing combining employment and retirement without promising the impossible gives people back some choice. Perhaps monthly earnings of €2,150 will remain out of reach for many. Then again, a more modest supplement may be enough to pay for glasses, help a grandchild or simply breathe a little more easily at the end of the month. Accurate information deserves to be shared, especially when it stops people giving up through fear.
| Key point | Detail | Benefit for the reader |
|---|---|---|
| Combining employment and retirement | It allows a person to receive a pension and employment income, subject to conditions. | Understand that returning to work can be lawful without automatically losing your pension. |
| The €2,150 | This amount is employment income, not a secret payment from Social Security. | Avoid misleading information and unrealistic expectations. |
| Checking beforehand | The pension fund must confirm which arrangement applies before any return to work. | Reduce the risk of suspension, exceeding a cap or subsequent adjustment. |
Comments
No comments yet. Be the first to comment!
Leave a Comment