
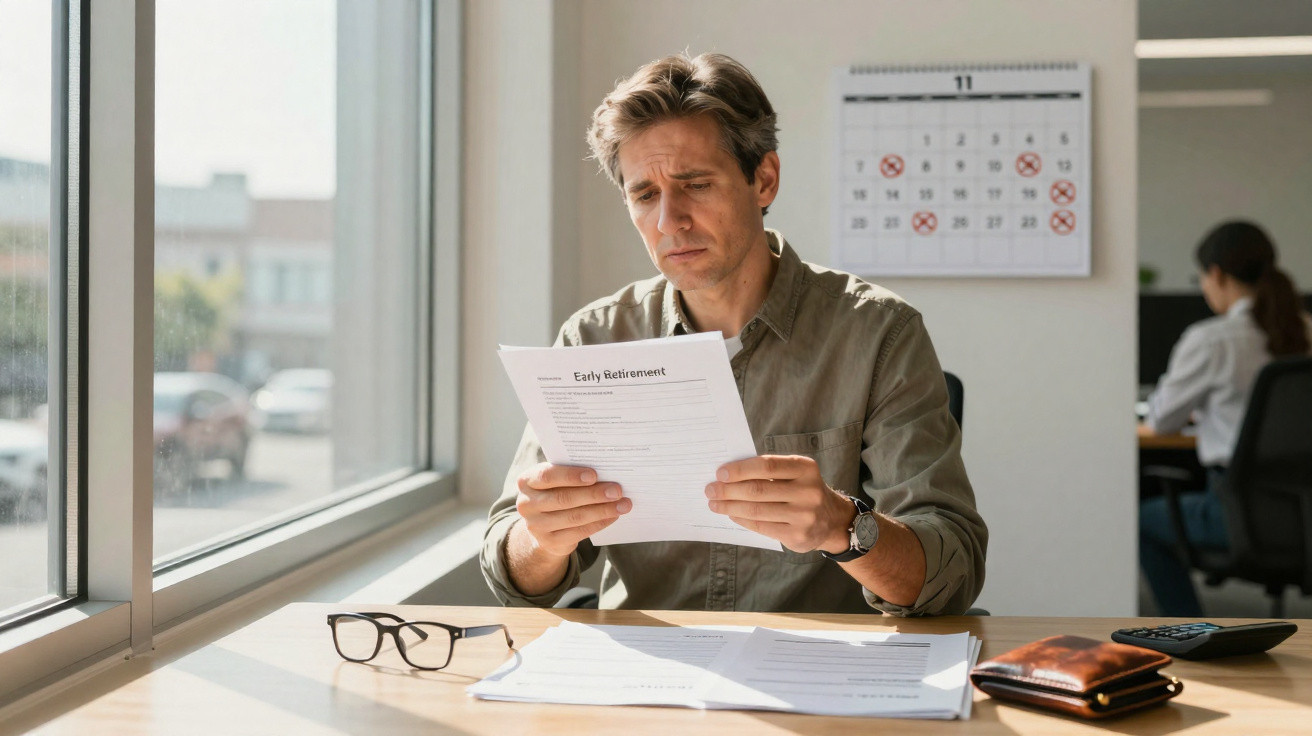
It is not a new law dominating the front pages. Instead, forms are being recast, evidence requirements redefined, thresholds subtly raised and an increasing pile of “not eligible” letters sent out. Thousands of people who expected to leave work months ago are now being told to remain-and the compensation payments they had budgeted for are evaporating like steam.
At 8:07 a.m., the pension office opens and the queue moves forward by a single person. A man in a faded parka holds a folder patched together with tape. He has recorded forty-one years of service, including night shifts. He smiles with the confidence of somebody who has fulfilled his obligations. The clerk asks for papers from 1987 that he no longer possesses, a job title that no longer exists and a “hardship” code that was not used at the time. Later, his HR department tells him that the lump-sum compensation he expected for leaving early no longer applies under new internal guidance.
That is how it feels when the rules shift beneath your feet.
The goalposts have moved.
The unseen tightening that has changed everything
The change is not limited to the statutory retirement age. It is also about the network of exceptions that once made early retirement possible for people with lengthy careers, poor health or demanding shift patterns. What once appeared to be a clear route now resembles a maze. Each stage calls for further evidence: a missing payslip, another document or a tougher interpretation of the same rule.
Consider Carla, a 60-year-old hospital aide who began working at 19. Her plan had been straightforward: leave this spring with a modest top-up and share a thank-you coffee with colleagues on the ward. Her record now contains two maternity-leave gaps requiring additional attestations. Her night work counts for less than expected because the “exposure” threshold has been recalculated. HR has withdrawn her bridging allowance, saying that the “early-exit category” no longer applies following the latest circular. Carla gives a polite smile, then returns to lifting patients.
These changes rarely attract headlines. This is administrative gravity: every memo cuts away an edge, every review turns another screw and every “clarification” makes an entry point narrower. Budget pressures matter, as do staff shortages and calculations based on longer life expectancy. Agencies are standardising definitions, digitising work histories, checking missing contribution years and reassessing “special cases”. On paper, that looks like routine administration. In practice, it means thousands must work longer while losing payments they were promised in good faith.
How to manage early retirement now: a practical, human guide
Begin by auditing your timeline. Ask the pension authority for your complete contribution record and obtain your National Insurance history. Then print both out-yes, on paper-and highlight anything unusual. Make a two-column list: “what I have” and “what they will ask for”. Search for older certificates, shift rotas, disability decisions and contract start dates. Request replacement attestations from previous employers using the precise wording required by current forms. If you worked nights or carried out heavy duties, collect proof of the hours worked rather than relying only on job titles. Build a file that stands firm.
The usual mistakes are simple, and deeply human. People leave matters until the final six months, despite discrepancies now taking nine to twelve months to resolve. They expect HR to identify a missing year connected to a subcontractor. They assume a doctor’s note automatically proves recognised “hardship”. We have all experienced the point at which life administration becomes overwhelming and gets postponed. Honestly, nobody manages it every day. Instead, start modestly: fifteen minutes, one document, one email.
One union representative told me that the emerging approach in some departments is “eligibility by attrition,” meaning delays themselves become the refusal.
“Your rights exist,” she said, “but they arrive so late you give up or time out.”
To push back, work with small deadlines and seek support.
- Submit your intention to retire early even if your file is incomplete, so that you secure a date.
- After 30 days, follow up politely with a recorded-delivery letter that cites the circular reference.
- When a benefit disappears, request the written legal grounds for the refusal.
- Take a witness or representative to meetings; keeping notes changes the dynamic.
- Maintain a log: dates, who said what and links to documents. It is tedious-and effective.
What is truly at risk: money, dignity and time that cannot be returned
This tightening creates more than bureaucratic stress. It can mean rent is unaffordable without another year of shifts. It can mean a grandparent misses school pick-ups, or a builder continues working with a back that will not stop spasming. It is a nurse enduring another night of alarms ringing in her ears, and a bus driver gripping the wheel at dawn yet again. Policymakers work with budgets and baselines. Workers live with calendars and bodies. Both sides belong in the story. Pensions can be protected while still respecting the shape of a working life. Perhaps that begins with plain language, clearer thresholds and an assumption that a long career means exactly what it says.
| Key point | Detail | Why it matters |
|---|---|---|
| Routes to early exit have narrowed | More evidence, redefined thresholds and a stricter interpretation of “hardship” | Fewer people qualify, even where their careers resemble those of people who qualified last year |
| Compensation payments are being reduced | Internal policies are reinterpreting who receives a top-up or lump sum | Workers lose the cash buffer they expected during the transition |
| Preparation is better than panic | Document checks, early applications and written escalations | Improves the likelihood of securing rights and avoiding expensive delays |
FAQ:
- What has changed if my legal retirement age has not changed? The eligibility rules for exceptions have become tighter. This means more paperwork, narrower definitions of “long career” and “hardship”, and fewer internal compensation payments linked to early exits.
- My contribution record contains gaps from decades ago. Am I finished? Not necessarily. Seek replacement documents from employers, tax or payroll archives, and sworn statements where these are permitted. Some agencies accept alternative evidence when original papers no longer exist.
- HR says the bridging payment has ended. Can I challenge it? Yes. Ask for the written legal basis, confirm when the policy changed and submit a formal appeal. If the change occurred after you filed your intention, transitional protection may apply.
- How far in advance should I prepare an early retirement claim? Ideally, begin 12–18 months ahead. This gives you time to correct records, collect medical or exposure evidence and meet new thresholds without a last-minute rush.
- Is help from a union or third party worthwhile? Often, yes. Experienced representatives know the exact wording, the relevant forms and the deadlines that progress a case. Even a one-hour review can save weeks of back-and-forth.
Comments
No comments yet. Be the first to comment!
Leave a Comment