
Anyone born in France who pays into its pension system will face a new framework for early retirement after a long working career from 2026. People born between 1965 and 1970 are particularly affected. Some will gain specific months, while others gain nothing at all - and what appears to be a minor date threshold could suddenly make a substantial difference to both income and time.
The issue: early retirement for long careers
France has a dedicated scheme for people who entered employment at an early age: early old-age retirement for a long career. It applies to insured people who began working before their 20th birthday and have built up a required number of insurance quarters.
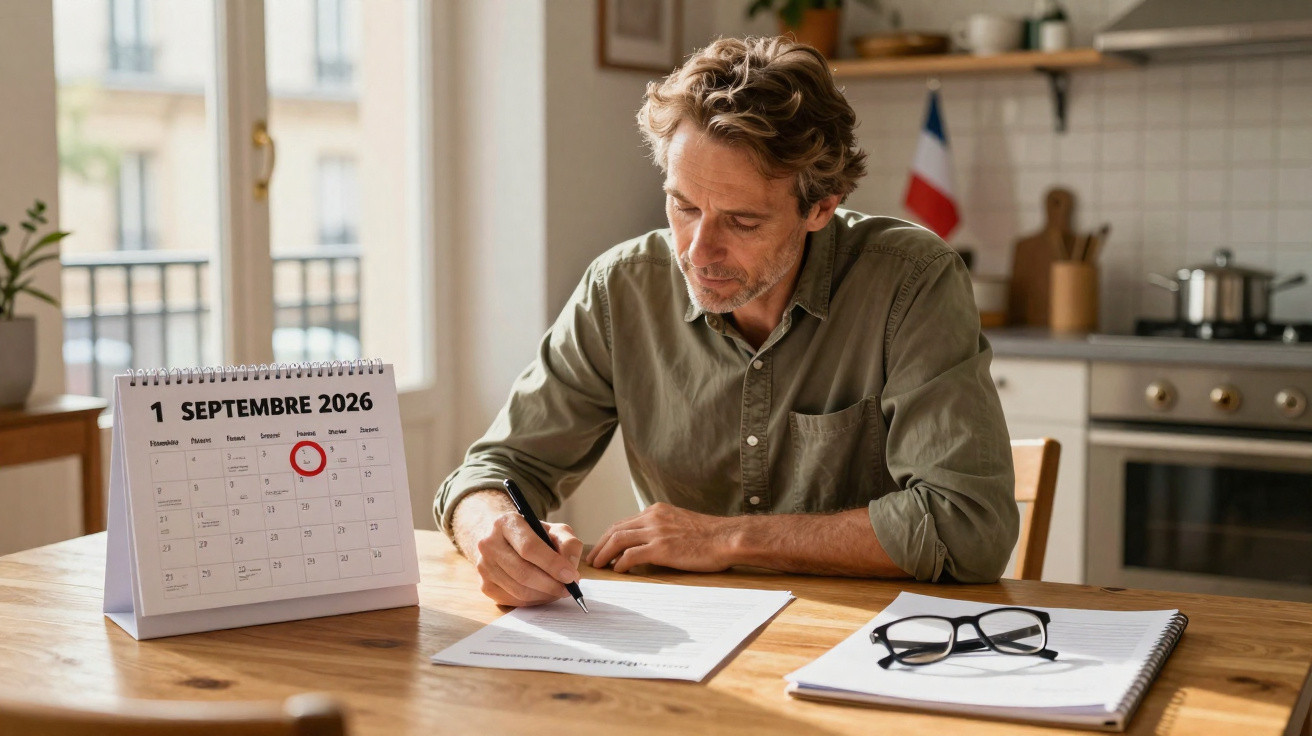
This rule is now being reorganised following the pension reform and its subsequent suspension. The retirement timetable is changing, although the basic eligibility criteria are not being completely rewritten. Above all, the date on which the new arrangements take effect is crucial: 1 September 2026.
The early retirement date for people with long working careers is being rescheduled - not every birth cohort will benefit, but some can gain up to three months.
New age thresholds for France’s long-career early retirement scheme
The French pension system has issued a revised schedule for long careers, meaning work started before the age of 20. It sets out the following earliest possible retirement ages:
- Born in 1964: no earlier than 60 years and 6 months
- Born from 1 January to 30 November 1965: no earlier than 60 years and 9 months
- Born from 1 to 31 December 1965: no earlier than 60 years and 8 months
- Born in 1966: no earlier than 60 years and 9 months
- Born in 1967: no earlier than 61 years
- Born in 1968: no earlier than 61 years and 3 months
- Born in 1969: no earlier than 61 years and 6 months
- Born in 1970: no earlier than 61 years and 9 months
Compared with the 2023 timetable, those born from 1966 to 1970 benefit most: their earliest possible retirement date moves forward by three months. People born in December 1965 still gain one month.
Why some people gain nothing
Those born in 1964, or during the first eleven months of 1965, are effectively excluded from the benefit. Their possible retirement age does not change, even though the rules are formally being amended.
The reason is straightforward: the slightly more favourable new timetable applies only where retirement starts from September 2026. By then, many of the older people affected will already have reached their previous age threshold, so the new rule arrives too late for them.
1 September 2026: a cut-off date with major consequences
For insured people with a long career, the date of birth is no longer sufficient on its own. The date from which the pension is actually paid is now also decisive. One example illustrates this:
- Man born in June 1965
- His personal early-retirement age: 60 years and 9 months
- He reaches that age in March 2026
If his pension begins in spring or summer 2026, the new timetable will not yet apply. He would therefore not benefit from any possible improvement. If he instead sets the pension start date as 1 September 2026 or later, the new provisions apply - allowing him to retire earlier or on better terms within those rules.
A different example:
- Woman born on 15 December 1965
- Her relevant age: 60 years and 8 months
- She reaches that age in mid-August 2026
In this case, the cut-off date has a direct effect. If the official pension start date falls before 1 September 2026, the previous position remains unchanged. If retirement begins on 1 September or later, the new, slightly more favourable figure applies - and even one month makes a difference.
It is not the birthday that decides matters, but the month in which the pension actually starts. Poor planning here can mean losing real money.
Eligibility: who counts as having a long career?
The fundamental conditions for early retirement remain unchanged. Anyone seeking to benefit in France must meet two main requirements:
- Early entry into working life: the first job subject to social insurance must have started before the person’s 20th birthday.
- Sufficient insurance record: a specified number of quarters is required, depending on the year of birth.
The current requirements for the relevant birth cohorts are as follows:
| Year or period of birth | Required quarters |
|---|---|
| 1964 | 170 |
| 1 January to 30 November 1965 | 170 |
| 1 to 31 December 1965 | 171 |
| 1966 to 1970 | 172 |
Which periods count - and which do not
Periods that can count towards a long career include, for example:
- insurance quarters accrued through ordinary employment
- maternity or paternity periods
- paid vocational training, such as an apprenticeship
- paid work placements
- military service or equivalent national service
Involuntary breaks, such as extended periods of unemployment, are not credited towards a long career, even if they may partially count towards other pension entitlements. Many people are surprised by how significantly this gap can delay their earliest possible retirement date.
The role of the Agirc-Arrco supplementary pension
In France, the Agirc-Arrco supplementary pension is particularly important for employees and managers. Its timetable follows the state pension: where a long career is officially recognised, Agirc-Arrco also pays the supplementary pension without a reduction, provided that the person meets the age and insurance-duration requirements for the state pension.
Put differently, people retiring early under the long-career rules do not face age-related cuts to their supplementary pension. This makes the technical details of the 2026 cut-off date even more financially significant.
A provisional framework - and what could happen after 2027
The new timetable for people born between 1965 and 1970 is based on a draft decree. The rules have not yet been published in the Official Journal and details may still change. Nevertheless, French authorities and online calculators are currently using this schedule to give insured people guidance.
There is also a political dimension. The current suspension of the latest pension reform will not continue indefinitely. After the 2027 presidential election, a range of outcomes is possible - from permanently freezing the current timetable to restoring the stricter schedule, or introducing an entirely new model.
What affected people should do now
Anyone born in France, born between 1965 and 1970, and who entered working life early should not simply wait for the standard pension date. It is worth checking three points closely:
- Date of birth: if it falls near critical thresholds such as December 1965, even one month can determine which timetable applies.
- Expected pension start date: will the pension begin before or after 1 September 2026?
- Quarters accumulated: do the contribution periods actually meet the long-career requirement?
Using this information, it is often possible to judge whether early retirement is realistic or whether a few additional months in work will still be necessary. Those close to the cut-off date may put themselves in a better position by delaying the pension start date by just a few weeks.
Context for readers in German-speaking countries
For people in Germany, Austria or Switzerland, the French system can often seem complicated, but it follows a recurring principle: those who began work especially early should not have to remain in employment until the full standard retirement age. At the same time, the state is seeking to keep costs manageable while putting the brakes on reform, hence the complex transitional arrangements and cut-off dates.
Cross-border workers who have worked in both Germany and France would be well advised to have their insurance records checked by both systems at an early stage. Different age thresholds, differing cut-off dates and the question of which periods are credited where can otherwise quickly lead to costly mistakes over the retirement date.
Comments
No comments yet. Be the first to comment!
Leave a Comment