
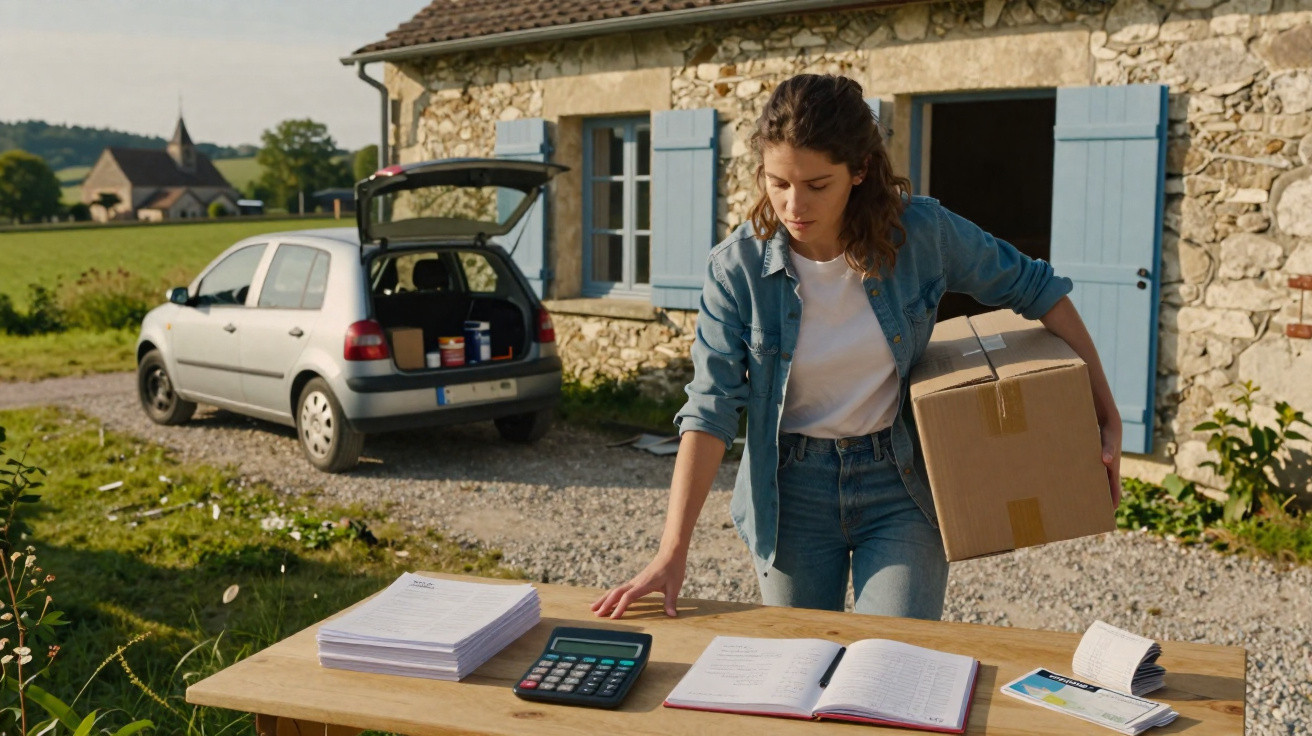
Each morning, Claire opens her shutters onto a garden still damp with dew, in a Creuse village where so few cars go by that you eventually learn to recognise their engines. Two years ago, she lived on the fourth floor of a Paris block of flats, with a dark courtyard opposite her window and the weekly refuse lorry as her alarm call. Her decision surprised her friends: leave Paris, buy a €150,000 house and learn to deal with bringing in firewood, long distances and sharper winters. Her budget has not vanished today; it has simply taken on a different shape.
In Paris, her rent already consumed a large share of her salary
For her 32 m² one-bedroom flat in eastern Paris, Claire paid €1,180 in rent, plus €95 in service charges. It was conveniently located, just 20 minutes from her office, yet space quickly became scarce whenever someone stayed on the sofa or she simply wanted to work from home in peace. We all know that point when we start viewing our home differently: no longer as a sanctuary, but as a bill that comes around too soon.
She started browsing property listings almost for fun, in the evenings, between two metro journeys and a series she had put on without much enthusiasm. Eventually, a 110 m² house with 1,200 m² of land, listed at €150,000 near Aubusson, caught her eye. Compared with Paris prices, the figure seemed unreal, but the first viewing also exposed a roof that needed watching, an outdated heating system and a 30-minute drive to the station.
Once the preliminary sale agreement was signed, Claire put in €30,000 of savings and borrowed €120,000 over 20 years. With an interest rate negotiated at about 3.55%, her mortgage repayment comes to roughly €695 a month, including insurance. That is lower than her former rent, though hardly miraculous: a house is never just a flat with a lawn added to it. Peace and quiet come at a cost, and it rarely arrives on a single bill.
What she actually pays each month for her €150,000 house
Claire now spreads her annual costs across the year to avoid fooling herself. She sets aside €70 a month for property tax, about €30 for home insurance and €25 for water. Her internet package costs €32, while electricity and heating average around €165 a month across the year, rising far higher when January grips Creuse with cold weather.
The item that has changed how she budgets is called “maintenance”. A gutter, a hedge, a sticking gate, a boiler needing its inspection: none of it is dramatic, but it all adds up. She therefore puts €120 aside every month in a separate account, even when there is no immediate problem. Let’s be honest: nobody really manages that every day. Yet this fund stopped her panicking when she had to replace a small lifting pump, which came with a €640 bill.
In total, excluding food and the car, Claire puts her housing costs at around €1,140 per month: mortgage, energy, water, insurance, internet, property tax and a maintenance fund included. She sums up what she has learnt with calm clarity.
“I’m not paying less in exchange for having nothing to manage. I’m paying differently, for space and the responsibility that comes with it,” Claire says.
- Mortgage and borrower insurance: €695
- Energy, water, internet and home insurance: €252
- Property tax provision and maintenance: €190
Car costs and renovations: the two expenses not to underestimate
The comparison with Paris looks less favourable once travel is added. Claire now owns a car, which is essential for shopping, medical appointments and journeys to the station. Fuel, insurance and servicing amount to about €230 a month, excluding any potential car loan. She chose a second-hand city car and paid for it outright, avoiding another monthly repayment. For her, country living does not mean living far from every expense.
A common mistake is to focus only on the asking price in a listing, then use the mortgage payment as the sole benchmark. Notary fees, moving costs, furniture suited to larger rooms and the first repairs soon follow, sometimes all in the same year. Claire retained €8,000 after her deposit, a cushion she now considers more reassuring than her large living room. An affordable house must also remain financially liveable.
Before buying, she recommends asking for previous energy bills, the exact property tax amount and the survey reports, then visiting the property at several times of day. A house that looks charming in May sunshine may reveal difficult access, noisy neighbours or persistent damp once autumn arrives. The most honest calculation is the one that includes a contingency for the unexpected, however modest, because small repairs never wait for the right month.
Moving region is not simply changing a line on your bank statement
Taking her housing and transport spending together, Claire is often between €1,350 and €1,450 per month, depending on the season and repairs. Her former Paris budget appeared more straightforward: rent, charges, the metro and a few deliveries when the weeks became overwhelming. In Creuse, she sometimes spends more in certain categories, but gains a guest bedroom, a hesitant vegetable patch and the rare feeling of no longer living on top of other people.
Her calculation would not suit everyone. A family with two cars, poorly insulated oil-fired heating or major renovation work will face a different equation, as will someone who has to travel back to Paris regularly. Conversely, working from home, a shorter loan that has already been well negotiated, or a highly energy-efficient house can bring the cost down. Figures provide a framework; real life always retains a few surprises.
Her move also reflects a weariness many people feel without always putting it into words: paying heavily to remain close to everything while sometimes lacking space, quiet or time. Claire does not claim to have found a formula. On some evenings, she misses the late-opening bakery and friends two metro stops away. On others, she looks at the sky from her terrace and thinks that her monthly budget now pays for more than an address: it funds a way of breathing, quite simply.
| Key point | Detail | Value for the reader |
|---|---|---|
| Monthly mortgage payment | Around €695 for €120,000 borrowed over 20 years | Compare the mortgage with your current rent, without forgetting insurance |
| Real cost of the house | Nearly €1,140 a month, excluding car and food | Plan for energy, property tax, maintenance and subscriptions |
| Point to watch | The car and renovation work can tip the budget | Build up emergency savings before signing |
Comments
No comments yet. Be the first to comment!
Leave a Comment