
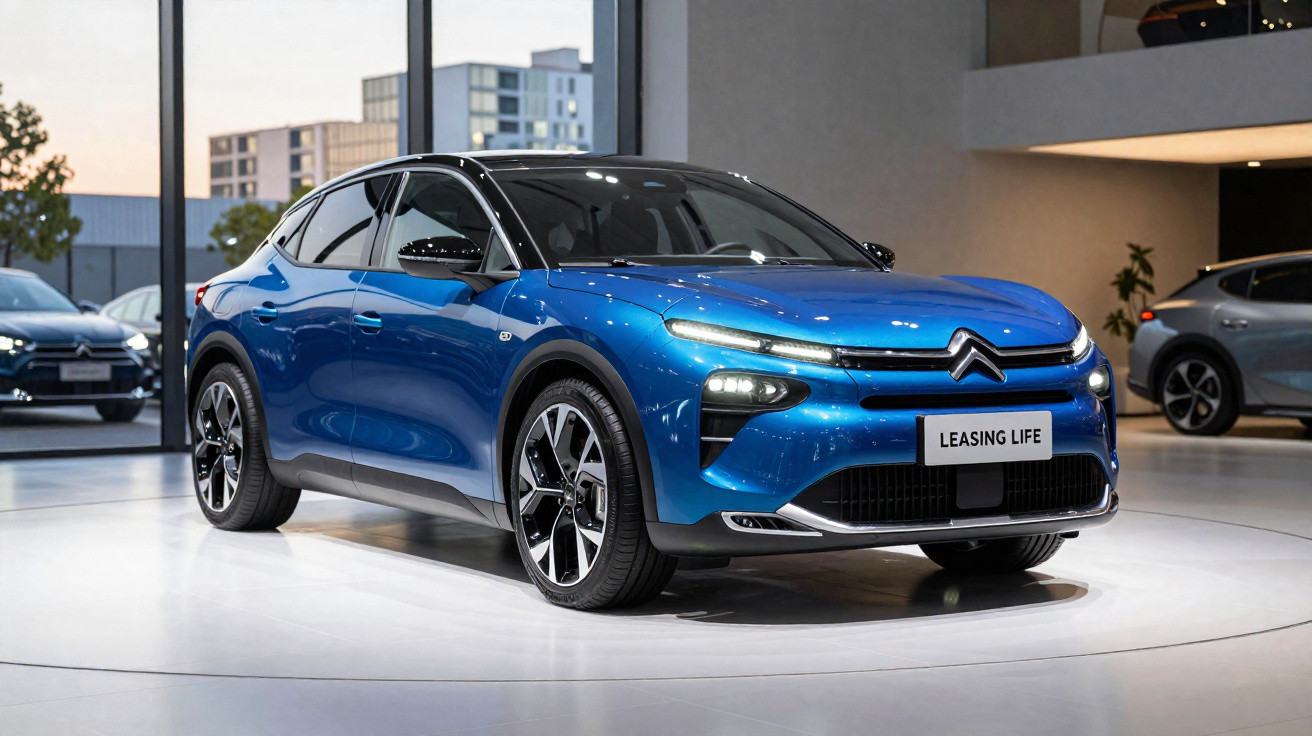
A family in southern France is trying to end a leasing agreement that has become a financial trap for their 94-year-old grandfather. He can no longer drive for health reasons and now lives in a care home, yet the bank continues to take almost €700 each month for a Citroën C4 that sits unused in a car park. The case raises a fundamental question: how effectively are very elderly people protected from the financial strain of complex contracts?
The surprise among the paperwork: leasing, not ownership
The arrangement came to light while the family was preparing the 94-year-old’s move into a care home. His grandson was sorting through files, bills and insurance documents when he found a substantial folder containing vehicle paperwork. The family had assumed that the older man had paid cash for his car several years earlier. Instead, they discovered a detailed leasing agreement.
He had signed the contract when he was 92. It concerned a nearly new Citroën C4 with an automatic gearbox, a 130 PS engine and a list price of more than €34,000. The deal ran for several years, with monthly instalments of almost €700 fixed until 2027.
“A 92-year-old signs a lease running for many years – and, two years later in a care home, the burden behind it becomes clear.”
On top of the monthly payments, the man had taken out several insurance policies, described as additional cover intended to provide security. According to the family, however, many of these policies are costly while offering little practical benefit in everyday circumstances. Some were cancelled retrospectively, but that did nothing to resolve the central issue: the leasing instalments.
His health declined and he lost the ability to drive – but the contract remains
The man’s circumstances have changed dramatically since he entered into the agreement. Now 94, he uses a wheelchair, lives in a care home and is no longer permitted to drive the vehicle. Doctors have confirmed that his fitness to drive is seriously limited, the authorities have responded, and his driving licence is no longer relevant.
The family initially hoped that the insurance policies taken out with the agreement might offer a solution. They assumed that at least one clause would apply if the leaseholder became permanently unable to drive or died. However, after examining the terms and conditions, they found there was neither effective incapacity cover nor genuine death cover linked to the lease.
The grandson describes the situation this way: even if his grandfather were to die, the family would generally still have to meet the contract payments until its end, unless they paid a substantial final settlement or early termination charge. The relatives regard that prospect as unacceptable.
Unsuccessful discussions with the dealership
The grandson repeatedly approached the Citroën dealership that had arranged the agreement. He gathered medical certificates confirming the man’s inability to drive, explained that he was living in a care home and appealed to the sales staff’s sense of responsibility.
According to his account, those efforts produced little result. Staff pointed to the signed agreement and argued that they could not have rejected a customer simply because of his advanced age. They could not merely say: “You are 92, you cannot have a leasing agreement,” because that could expose them to allegations of discrimination.
“The dealership’s central message: the agreement stands – either pay until 2027 or take over the car for a high remaining sum.”
For the family, both options presented by the dealership appear to be a trap. They can either continue paying €700 a month while the car remains unused, or settle the vehicle for more than €20,000 – money that is much more urgently needed for care costs and daily living.
Grey area between freedom of contract and protection from exploitation
The case illustrates a conflict familiar in many countries. On one side is freedom of contract: even a very elderly person is generally entitled to decide independently whether to sign a loan, lease or insurance agreement. On the other is the risk that people with early-stage dementia, reduced judgement or simply limited experience may be overwhelmed by such decisions.
In situations like this, lawyers often refer to the possible “exploitation of a position of weakness”. Whether that accusation applies in this particular case would ultimately be for the courts to determine. The evidential threshold is often high: it must be shown that, when the contract was signed, the person could not understand its consequences and risks, and that the other party knew this or should at least have recognised it.
Common issues with contracts in later life
- Complex contractual terms that even younger people can scarcely understand in full
- Add-on insurance policies that are expensive but provide little when they are actually needed
- Long contract periods extending far beyond average life expectancy
- High residual values or final payments that can take relatives by surprise
- Little or no involvement of family members or trusted advisers
What relatives can learn from this case
Although this case took place in France, the issue is highly relevant in Germany, Austria and Switzerland. Leasing, hire purchase and subscription models are now part of everyday life, while car dealerships, electronics retailers and banks actively promote apparently low monthly payments.
People with older relatives can take preventive steps to avoid unwelcome surprises. Clear family arrangements can help: once someone reaches a certain age or their health begins to decline, a second person should always review major contracts, long-term subscriptions or loans.
Useful measures include:
- Reviewing bank statements and direct debits regularly, provided the person concerned agrees.
- Checking insurance and leasing documents, particularly when new agreements are being made.
- Discussing fitness to drive and road-safety risks openly with the GP.
- Where appropriate, arranging a lasting power of attorney or legal support before the situation becomes critical.
Legal action – a final option with an uncertain outcome
In this case, the family is now openly considering court action. They accuse the dealer of a form of exploitation and a lack of responsibility: a 92-year-old with known health problems was given a powerful saloon car under a long-term leasing agreement, without any meaningful safeguards.
Court proceedings could establish whether the agreement can be challenged on the basis of lack of legal capacity, deception or other grounds. Such cases often take a long time, cost money and cause considerable stress, with no guarantee of success. Even so, many relatives see legal action as their only chance of escaping commitments they consider financially ruinous.
At the same time, there is a wider debate about whether legislators and consumer protection bodies should tighten the rules. Possible measures could include stricter requirements for financial products sold to people above a certain age, such as shorter terms, enhanced advisory duties or compulsory checks that a person can understand the agreement without assistance.
Leasing in later life: sensible alternative or ticking time bomb?
Leasing can be attractive to younger drivers: newer technology, predictable payments and no need to worry about reselling the car. In later life, however, priorities can change. Health may deteriorate within months, driving can become riskier and the need to retain funds for care can increase.
Anyone who still needs a car at 80, 85 or 90 should consider several points particularly carefully:
- Contract term: Keep it as short as possible to retain flexibility.
- Monthly payment: It should remain affordable even if care costs rise.
- Insurance: Examine closely which additional policies are genuinely worthwhile.
- Exit options: Check clauses covering illness, loss of a driving licence or death.
- Family involvement: Take a trusted person to the consultation meeting.
For the 94-year-old, two clocks are now running at once. One is the leasing agreement, draining money month after month. The other is the search for a fair outcome, whether through renewed talks with the dealership or ultimately in court. For many readers, the conflict will be obvious: the human reality of life in a care home is colliding head-on with the rigid logic of a financial contract.
Comments
No comments yet. Be the first to comment!
Leave a Comment