
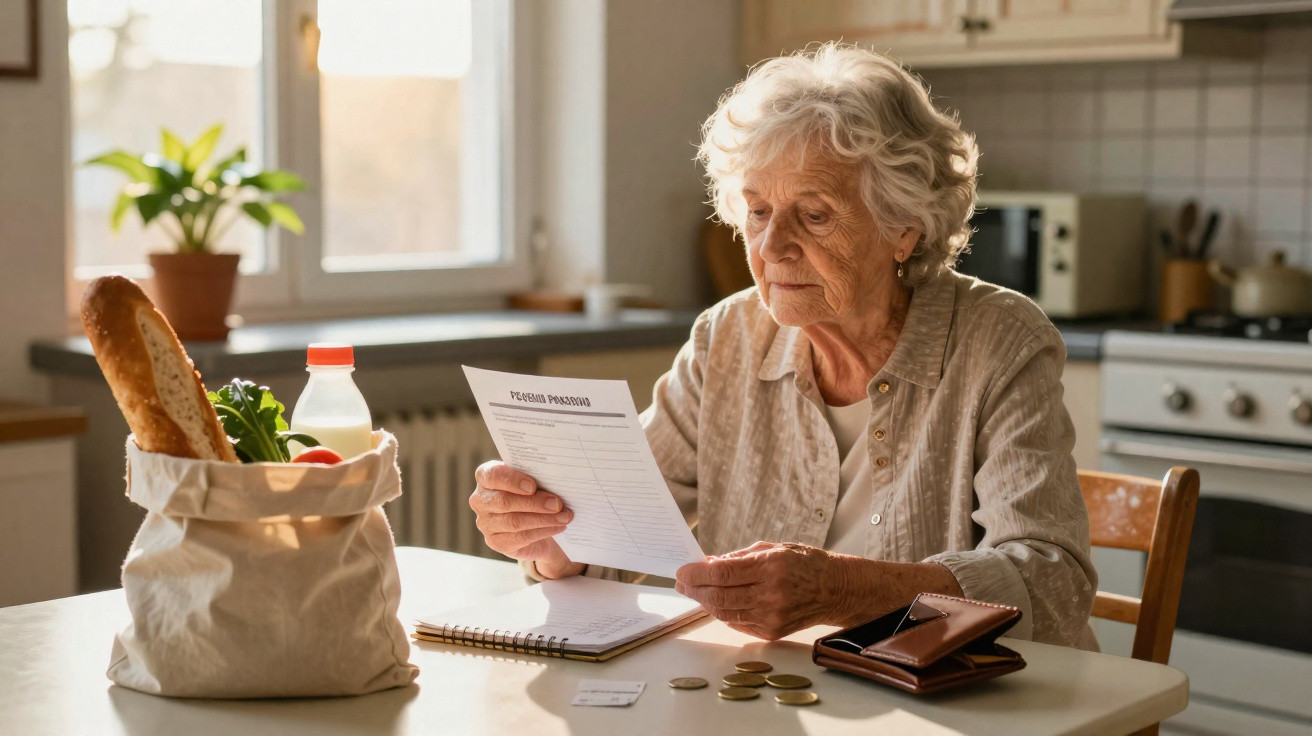
A white envelope arrives, bearing ordinary print - the sort of post you might leave unopened for a day or two. Yet inside, two brief lines alter everything: the state pension you depend on each month will be reduced by £140 from December 2025. It will not be held at its current level. It will be cut.
You look again at the amount: £140. It could cover food, heating or bus journeys to visit grandchildren. It is the narrow buffer that has changed merely getting by into managing, more or less. Throughout the country, millions of pensioners are opening an identical letter and doing the same sums at their kitchen tables.
Some people carefully fold the sheet away. Others crush it in their fists. A few simply look at it. Each is left with the same unspoken, or spoken, question.
What happens next?
What a £140 state pension cut means in everyday life
The announcement is now official: state pension payments will fall by £140 each month from December 2025. It is a neat administrative statement that conceals the disruption it causes in ordinary lives. In a document, it may be described as a “budget adjustment” or “long-term sustainability”. In reality, it is Sandra in Leeds asking herself which direct debit will fail first.
These are people already living exceptionally close to the edge. For many, the state pension is not additional money. It pays the rent, buys medication and covers the weekly food shop. This £140 cut is not absorbed by a generous, comfortable household budget; it lands on a financial tightrope.
A single figure in black print can put countless everyday decisions back on the table.
Consider Colin, 73, from Birmingham. He worked on building sites for 45 years, getting up at 5 a.m. during winter and carrying on despite back pain and damaged knees. His monthly finances now depend entirely on the state pension, a small workplace pension and the occasional income from letting his spare room to language students twice a year.
He gave up holidays, replacement clothes and meals out long ago. His one weekly pleasure is fish and chips on Fridays, along with a pint shared with an old colleague. On hearing about the £140 reduction, he takes out the old notebook in which he records every pound. He crosses out fish and chips, then pauses before adding a question mark beside the heating allowance.
On paper, £140 can be presented as “around £4.60 a day”. In daily life, it can mean choosing between another hour of heating and buying a train ticket to visit a friend in hospital. Such small changes are absent from policy papers, yet they quietly shape real lives.
The reasoning behind the reduction will sound familiar: a growing older population, strained public finances and political leaders arguing that the system cannot continue “as is”. The state has committed to paying more people for longer without equivalent rises in tax receipts or stronger economic growth. Eventually, the calculations reach breaking point.
December 2025 has not been chosen by chance. The timing fits fiscal cycles, spending reviews and years of economists issuing warnings. Their message has been consistent: the present pension model is under strain. Governments deferred difficult decisions for as long as possible, and those decisions are now arriving on pensioners’ doorsteps.
At one end is the wider economic narrative - deficit targets, bond markets and fairness between generations. At the other is June in Portsmouth deciding whether broadband or fresh food must go. The policy applies across the country, but its impact is intensely personal.
Preparing for the £140 state pension cut before December 2025
Waiting until the first lower payment reaches your bank account is the least helpful approach. Even when you feel unable to act, one modest practical step is better than general anxiety. Begin with a straightforward, almost traditional exercise: map out your monthly finances. Start with your current pension income, take away £140 and write down the resulting figure.
Next, compare that amount with what you genuinely spend. Do not use the idealised budget you imagine you follow; use the money that actually leaves your account each month. Mark the costs that cannot truly be avoided, including rent, essential bills and medication. The remaining spending is not necessarily frivolous, but it can be adjusted. Those are the first areas where you may be able to make changes before the reduction begins.
This is not about reducing your life to a spreadsheet. It is about preventing the late discovery that one direct debit is enough to push you into an overdraft.
Financial pressure in later life often brings an unusual sense of shame. People can believe they “should” have put more aside, planned more carefully or made better decisions. Life, however, rarely unfolds like a personal-finance leaflet. Divorce, illness, redundancy and caring for parents or children all leave their mark on a bank balance.
If news of the pension cut leaves you with a knot in your stomach, you are certainly not the only one. Speak with somebody you trust: an adult child, a neighbour or a local advice charity. At the most basic level, saying “£140 less each month will hurt” aloud can already change the way your mind tackles the issue.
Let us be honest: nobody really does this every day. No one reviews their budget with military precision week after week. However, during the twelve months leading up to December 2025, a few purposeful reviews can prevent minor financial leaks from becoming overwhelming problems.
The emotional impact of a pension cut remains quietly present behind the figures. A financial counsellor told me something memorable:
“People think they’re bad with money. Most of the time, they’re just trying to solve yesterday’s problems with today’s income.”
The £140 cut places more people in that difficult gap. You may therefore need to look beyond the spreadsheet and consider the wider picture: have you left unclaimed support untouched? Are there benefits you assumed you would not receive? Have you overlooked local schemes because you did not want to trouble anyone?
- Check whether you qualify for Pension Credit, housing support or a council tax reduction, even if an earlier application was unsuccessful.
- Contact your energy supplier about hardship funds or priority services before winter 2025.
- Consider modest, achievable ways to supplement your income, such as a few hours of work each week rather than an entire second career.
Some of these actions can feel uncomfortable. They can challenge your pride and the sense that you have “managed so far”. Even so, they may lessen the harshest effect of the £140 reduction.
Living on less and what the state pension cut says about society
When the reduction takes effect, life will not stand still. People will adapt, as they always have, in ways that are both admirable and quietly distressing. Some will move in with relatives. Some will sell a car they use less often than they care to admit. Others will become highly skilled at batch cooking and searching supermarkets for yellow-sticker reductions - because that is a skill.
At a personal level, the first losses are often the flexible parts of a budget: social outings, small presents and trips away. They are the small routines that make life feel worthwhile. That is the true danger of cuts of this kind: not only financial deprivation, but a gradual narrowing of people’s worlds. Fewer visits, more refusals and more time at home because a bus fare has become a luxury.
At a national level, this also prompts a difficult question: collectively, what sort of later life are we prepared to accept in this country?
When news like this emerges, many readers speak of anger. The feeling is directed not solely at “politicians”, but also at the impression that the deal has been altered unilaterally. You work, contribute, accept later retirement ages and changing rules, then expect at least a basic level of security in old age. A state pension cut can feel as though that line has shifted overnight.
There is also an understated tension between generations. Younger adults ask: “Should we really be paying more tax for pensions when we may never get one ourselves?” Older people answer: “We helped build the system you’re in.” These conversations are not straightforward, but the £140 cut brings them into families whether they are prepared for them or not.
Most of us have already experienced the moment when money unexpectedly becomes the main subject at a Sunday lunch table. Someone mentions a number - rent, bills or pensions - and the atmosphere changes. This reduction will add more such moments to the calendar.
Perhaps the most unsettling reality is that one policy can reveal more about a society’s genuine values than a hundred speeches. Reducing the state pension by £140 is not merely a technical alteration. It is a decision about who bears which burden when finances become tight.
The coming year and a half is therefore not just about budgets and ways to survive. It is about discussion - between generations, neighbours, voters and those they elect. Who is protected? Who faces the pressure? Who is quietly instructed to “tighten their belt” when there is no belt left to tighten?
These are not theoretical questions. They are there in that white envelope on the table.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| Amount of the cut | Official reduction of £140 a month from December 2025 | Know exactly what to expect from every payment |
| Preparing in advance | Create a budget now with £140 less | Reduce the shock and avoid unexpected overdrafts or debts |
| Available support | Pension Credit, housing support, energy funds and budgeting advice | Identify practical resources that may offset part of the reduction |
FAQ:
- Will every state pensioner lose £140 a month? The reduction is presented as a standard monthly cut, although the effect on your precise entitlement may differ. Check your individual forecast through the official government portal or with a trusted adviser.
- Does this affect both the basic and new state pension? Yes, the measure is intended to affect total state pension payments. Whether you receive the basic state pension or the newer system, the reference point is a net monthly decrease of £140.
- Can this decision still be reversed before December 2025? Officially, the reduction has been approved. In practice, a new government or policy change could reconsider it. That remains possible, but basing your plans on the expectation of a reversal is risky.
- What if £140 less means I cannot cover essentials? This is exactly the point at which to seek support: Pension Credit checks, local welfare schemes, debt-advice charities and energy-support funds exist for cases where essential costs cannot safely be met.
- Is there anything small I can do that genuinely makes a difference? Yes. An honest, simple budget review, applying for one new benefit or discount and discussing the change openly with family can often make a greater difference than you might expect from one step alone.
Comments
No comments yet. Be the first to comment!
Leave a Comment