
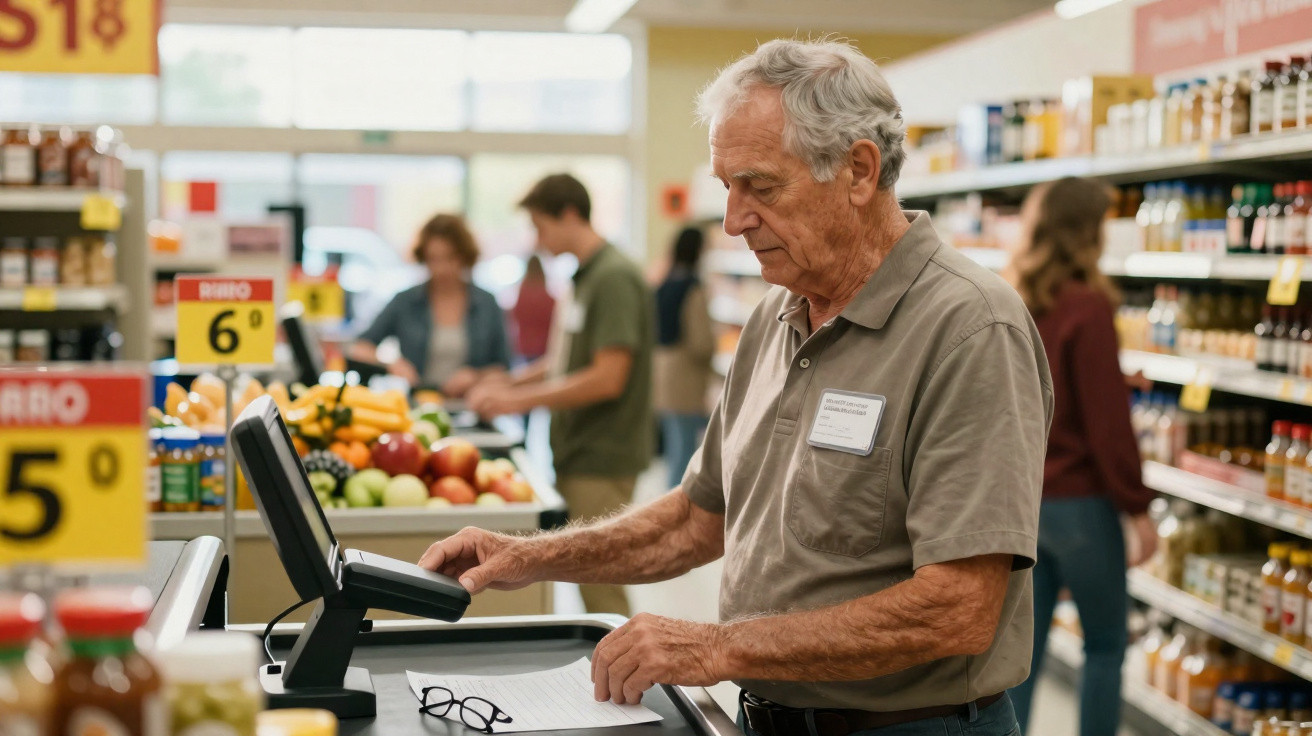
At around 6.30 am, Mr Krüger pulls crates of bread rolls across the car park of a supermarket in a medium-sized German town. He is 72, once an insurance administrator and now a mini-job worker on the early shift. The shop’s neon lights flicker while he fills the shelves. He jokes with the young colleague on the till, but when she briefly walks away, his eyes settle on the butter price board. €2.49. He exhales quietly, more to himself than anyone else. “I never used to think about things like that,” he mutters as he puts away the final crate. Now he calculates the cost of every pack in his head: electricity, heating, and how much of the month will be left once the money has gone.
You can sense it: behind his smile, a mental calculator keeps running and never switches off.
When retirement suddenly exists only on paper
You see them everywhere once you start looking properly: older men with grey beards stacking shelves; women in their mid-seventies behind bakery counters, despite having long reached retirement age; and voices on the bus apologising with, “I’m actually already retired,” when boarding takes a little longer. They wear safety shoes rather than slippers. Many would far rather be sitting at the kitchen table in their pyjamas each morning than standing in workwear in a DIY store car park.
The raw figures are difficult to overlook. In Germany, the number of working pensioners has risen noticeably in recent years, by double-digit percentages in some regions. Former tradespeople are now delivering parcels, while previous teachers sort products onto shelves in chemists. The official explanation is often, “I need something to do, otherwise I’ll go mad.” Ask more closely after a few minutes, however, and another sentence usually follows. A quiet, brief one: “Otherwise, I can’t manage on my pension alone.”
The reasoning is brutally straightforward. Living costs are increasing: rent, energy, food and insurance. Pensions may rise on paper, but the benefit disappears as soon as the next direct debit leaves the account. Many pensions reflect working lives interrupted by raising children, part-time work, caring for relatives or periods of unemployment. Women in particular feel the impact in their wallets every month. Anyone who has spent their whole life “somehow managing” may suddenly discover in later life that “somehow” is no longer enough. Then, at 68 or 74, they find themselves wondering whether to buy another work jacket.
Between dignity and discount-store jobs: making work in retirement feel less harsh
Some pensioners take a surprisingly strategic approach to continuing to work. They sit down, work through the figures carefully and speak to the pension insurance service or a wage-tax advice association. It is not all sentimentality or “I simply like helping in the shop”. Those with room to manoeuvre deliberately cut their hours, look for physically easier roles or move their shifts to early mornings or evenings so that the daytime remains free. Sometimes voluntary work with a local association develops into a small paid role. In other cases, long-standing expertise is turned into consultancy. “I have to” becomes, at least in part, “I choose to”.
Typically, many people begin too quickly and with too much goodwill. They say, “Of course, I can do that,” and accept every shift, every call and every extra task. Eventually, their bodies apply the emergency brake. Their backs, knees and circulation all start protesting. Let us be honest: nobody enjoys leaving home at 4.30 am five days a week at the age of 70. Some say they initially feel ashamed even to admit that they need to work again. A sense of having “failed” hangs over them, as though they had personally planned badly. In reality, they are usually paying the price for decades of political and economic decisions.
In the café of a small town, a 69-year-old former nursery teacher sits after spending a few hours caring for children, paid by young parents. She says:
“I love children, that is not the problem. But I would have liked to decide for myself whether I did this – rather than doing it because heating becomes a luxury in winter otherwise.”
She has set out a few rules for herself:
- Never accept more than three fixed working days per week
- Favour jobs that suit existing knowledge and personal physical capacity
- Agree in writing beforehand what will be paid for – and what remains a favour
- Talk openly with the family about money, pressure and boundaries
In this way, compulsion gradually becomes a framework with room for personal choices.
When work in retirement becomes a quiet public vote
The growing number of working pensioners is more than an economic statistic; it is something like a quiet vote with their feet. They are signalling that the story of a carefree retirement no longer matches many bank balances. Some see this trend as a silent scandal, while others regard it as the sober reality of an ageing society. Between these two poles are real people standing by bakery shelves at six in the morning or making beds in care homes at night. What hardly anyone tells them is that they are supporting the system again, despite having already supported it throughout their lives.
Perhaps, in a few years’ time, we will tell different stories about old age. Less about “a well-earned retirement” and more about negotiating together: how do we want to live when we are old? How much work is reasonable, how much financial security do we expect, and how much are we prepared to grant one another? When people see a pensioner smiling in a supermarket today, they often see only the surface: a little movement, a conversation, a task. Beneath it lies the stark question: is there enough money for a life that is not simply about getting through?
Perhaps change begins precisely when we stop looking away as the 74-year-old parcel delivery driver stands at the door, breathing heavily. Instead, we start a conversation, ask about his story and allow ourselves to feel our own anger or helplessness. Then we ask how we want to think differently not only about our own old age, but also that of our parents and neighbours. Working in retirement is no longer an exception; it has become the norm. The question is: do we want that to remain the case, or will we eventually tell ourselves different figures, different stories and different visions of the future?
| Key message | Detail | Value for the reader |
|---|---|---|
| Pensions often no longer cover basic costs | Rising prices coincide with interrupted working lives and low pensions | Assess your own financial position in later life more realistically |
| Continuing to work can be shaped | Choose hours, roles and conditions consciously | Practical ways to turn compulsion into greater self-determination |
| Open conversations ease the pressure | Shame about money worries decreases when family and those around you are involved | Make better use of emotional and practical support |
FAQ
- How many pensioners are currently continuing to work? Depending on the region, around one in six to one in seven pensioners continues to work in some form, and the trend is rising.
- Can pensioners earn unlimited additional income? Since the Flexible Pension scheme, the limits have been eased considerably; nevertheless, it is worth checking the current rules of German Pension Insurance.
- Is an advice appointment worthwhile before taking a side job? Yes. Even a one-hour conversation with the pension insurance service or a wage-tax advice association can prevent later financial surprises.
- Which jobs tend to be more manageable for older people? Roles involving little heavy lifting, flexible hours and the use of existing experience – such as care, office work, consultancy and light service jobs.
- How should I talk to my parents about working again? Without blame or pity: listen, ask what is putting pressure on them, and look together for alternatives or ways to ease the burden.
Comments
No comments yet. Be the first to comment!
Leave a Comment