
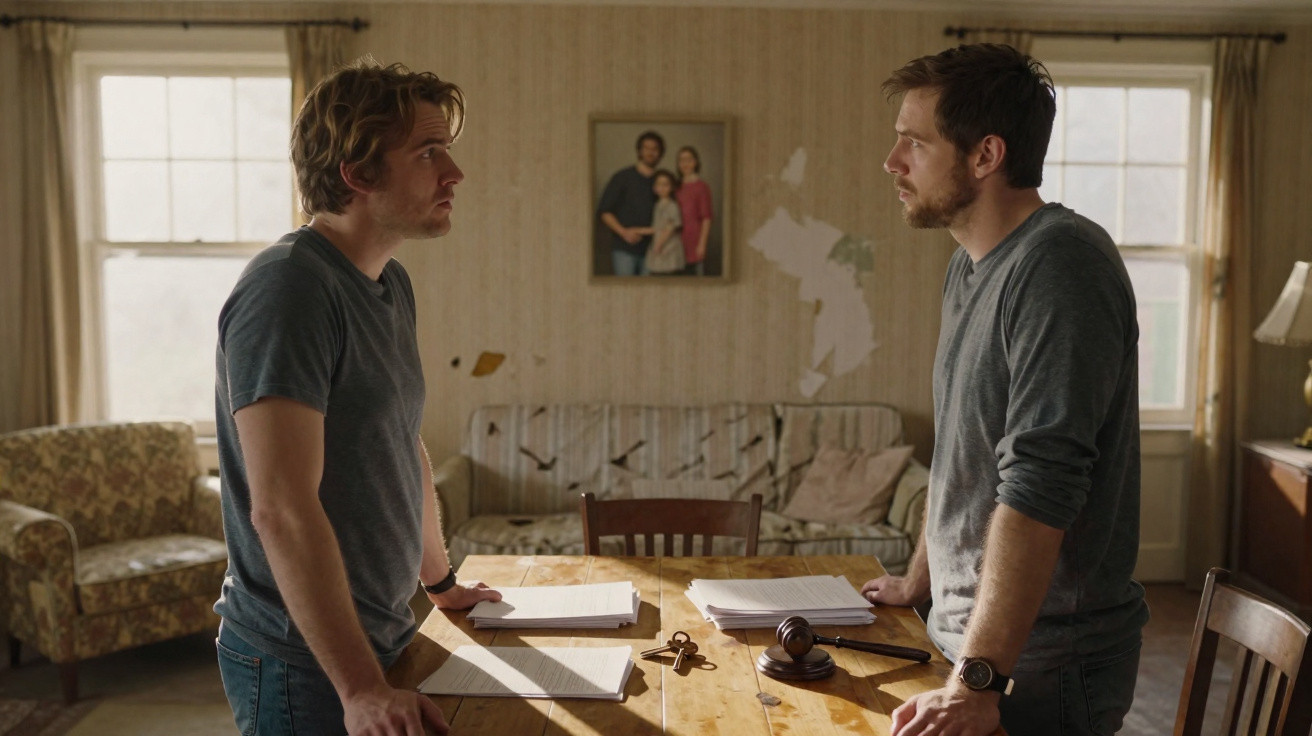
The peeling wallpaper was the first detail they learnt to overlook. After that came the damp smell, creeping up the stairs week by week like a silent warning nobody wanted to acknowledge. Their father’s old family home was meant to be his gift to them: the final piece of him that the three siblings could share. Instead, it turned into a battleground, visited only for photographs, recorded-delivery letters and conversations conducted through solicitors.
One wanted to sell; another wanted to preserve everything “as it was”; the third remained caught between them, watching the property deteriorate while the unpaid bills mounted.
A weathered “For sale” board fluttered on the gate.
But the real storm was unfolding in the family WhatsApp group.
When an inheritance dream becomes unpaid work
An inheritance can sound like a blessing when it appears merely as a line in a notary’s letter: a house, some land, perhaps a little savings. On paper, it can feel like an unexpected bonus that life never owed you. Then the calls from the tax office begin, insurance reminders arrive, and the notary sends an uneasy email asking for “a clear position from all heirs”.
What first appeared to be a gift can suddenly resemble a part-time job: no wages, no holidays, only obligations.
When the heirs are siblings who cannot agree on the next step, a house may be left in an odd limbo. Nobody truly lives there, yet everyone quietly funds its gradual decline.
Consider this familiar situation. Three brothers inherit their parents’ old house in a small town. The youngest lives close by and keeps his tools in the garage. The eldest, who lives abroad, wants to sell promptly and “move on”. The middle brother holds on to the idea of renovating it someday, “when things calm down”.
Nobody wants to play the villain, but nobody wants to pay for major repairs either. As the years pass, paint begins to flake, the roof develops leaks and damp takes hold.
The bills, however, do not pause. There is property tax, co-ownership charges, insurance for an empty home and utility costs needed to stop the pipes freezing. The house steadily drains everyone’s bank account, but the deeper harm lies elsewhere: in the resentments that become firmer every time a message receives no reply.
Legally, indifference also carries a price. In many countries, heirs become jointly responsible for inherited property as soon as they accept the inheritance. If nobody takes action, the debts do not vanish; they simply fall on all of their shoulders.
Judges regularly encounter these cases: one sibling pays “to avoid trouble”, another refuses to contribute a penny “until we agree on the big picture”, while a third disappears altogether. Once the dispute reaches court, the judge is not concerned with who wept most at the funeral.
The court examines who used the house, who paid for what and who obstructed which decision. It then decides who must ultimately meet the cost of a roof nobody repaired.
From family drama to legal reality: who pays when no one agrees?
One step often changes the whole situation: applying to end the joint ownership. Behind this dry legal term is a straightforward message to the court: “We’re stuck. We can’t manage this together. Decide for us.”
That application can result in a forced sale of the property, with the judge overseeing both the process and the division of the proceeds. It can be emotionally brutal, particularly where the property is the family home, but it ends the steady drain of unpaid bills and endless disputes.
It also requires everyone to replace vague assurances with figures. How much has each sibling paid already? Who occupied the house? Who allowed the garden to become so overgrown that clearing it now costs thousands?
The main trap for many families is waiting “just a little longer”. One sibling moves into the home “for a few months”, pays no rent and never formalises the arrangement. Another covers every tax bill for ten years, only to discover that they must prove each individual payment if they seek reimbursement.
Realistically, hardly anyone keeps every receipt and bank statement perfectly organised for a full decade. Yet those are often the documents judges need when deciding who should bear the financial burden of a decaying house.
What seems “fair” at the family table does not always accord with the law. A person who has sole use of the property for years may be treated by the court as owing rent to the other heirs. Equally, someone who rejected every offer to sell cannot later claim that the property was a burden they never chose.
In these disputes, judges effectively carry out a moral reckoning through legal means. They assess three central factors: benefit, inertia and effort. Who benefited from the property? Who prevented solutions? Who actually paid to avert disaster?
A sibling who enjoys the house without charge, stores possessions there or lives there almost full-time may be regarded as having received an advantage. The sibling who pays tax and emergency repair costs may seek compensation. The one who says nothing for years and only emerges when the property is sold risks appearing less credible.
The court doesn’t heal old family wounds, it just writes them into a judgment.
For instance, the judgment may require the sibling who occupied the property to repay part of the expenses, or deduct repair costs from their share of the sale proceeds. Cold calculations imposed on deeply felt memories.
How to prevent an inheritance becoming a legal life sentence
The first meaningful step often takes place well before any judge is involved: siblings should put the arrangement in writing, even if it is only an email. “You live in the house, you pay this. I pay that. We talk again in six months.” It need not be flawless; it simply needs to exist.
If one person uses the home, agree a modest rent or compensation, even if it is symbolic. If someone pays a large bill, circulate the invoice to the others and record everyone’s response. These basic practical measures create an evidence trail that a judge can later understand.
A brief written agreement prepared with a notary can also set the rules in place: who is responsible for what, what each person pays and for how long. It does not take away the grief of bereavement, but it can prevent the shock of waking up one day to a court claim.
The most frequent error is mistaking loyalty to the past for unquestioning loyalty to bricks and tiles. Keeping the house “because it was Mum’s” may sound romantic, until you are cleaning mould from the bathroom on a Sunday morning while arguing over a plumber’s estimate on speakerphone.
We have all experienced the moment when agreeing feels easier than confronting a dispute. You accept the inheritance without asking serious questions, allow your brother to “handle the paperwork”, and nod when someone says “we’ll see that later”.
But later arrives, accompanied by late-payment charges, court summonses and the sickening feeling of seeing the family name on an official envelope. Admitting that you cannot afford to maintain a house, or that selling is the only way to protect those still living, is not a failure. It is simply honest.
Sometimes, the most loving decision you can make for a dead parent is to stop sacrificing the living for a piece of property they no longer need.
- Talk early – Within a few weeks of the inheritance, arrange one clear discussion involving every heir, ideally with a neutral third party such as a notary or trusted friend.
- Put it in writing – Even an imperfect email summary of “who pays what” may become invaluable if the disagreement later escalates.
- Set a deadline for decisions – Agree when you will decide whether to keep, let or sell. An indefinite “we’ll see” is how homes decay and relationships fracture.
- Record every expense – Maintain a simple shared document for tax, repairs and insurance, stating who paid and when. Your future self will be grateful.
- Seek help before court – Mediators, notaries and legal clinics are available. The sooner you speak to somebody neutral, the more options remain open.
When an inherited house outlives the family that built it
There is something particularly cruel about seeing a house crumble while siblings argue over who loved their parents most. The roof does not care. The garden does not care. The court certainly does not care.
What began as a symbol of togetherness can become a mirror for every perceived injustice, childhood rivalry and old remark that still stings. Some siblings do not speak for years because of a dilapidated garage or a dark, unused sitting room. Others manage to sit around the kitchen table one final time, sign the sale documents, then have a coffee together: partly relieved and partly heartbroken.
These situations do not fit neatly into legal categories. A judgment can determine who pays, who owes money and who receives which share of the sale. It cannot determine who will appear next Christmas.
Perhaps that is the real question beneath the damp walls and unpaid bills: what are you prepared to lose to keep a house, and what are you prepared to release in order to keep a brother or sister?
| Key point | Detail | Value for the reader |
|---|---|---|
| Put rules in writing quickly | Specify who uses the property, who meets each cost and for how long | Reduces surprises and provides solid evidence if the conflict reaches court |
| Use legal tools before it is too late | Ask a notary, mediator or judge to end joint ownership or require a sale | Halts the financial drain and avoids a “life sentence” of endless co-ownership |
| Separate emotion from responsibility | Recognise that memories are not the same as bricks and unpaid tax | Supports calmer decisions and protects both your money and your relationships |
FAQ:
- Question 1 What happens if I refuse to pay my share of the house expenses as an heir?
- Answer 1 Other heirs may pay on your behalf and then ask a judge to reimburse them from your share of the inheritance or directly from you. Courts generally regard co-heirs as jointly responsible for essential costs such as tax and urgent repairs.
- Question 2 Can one sibling force the sale of the inherited house?
- Answer 2 Yes. In many legal systems, nobody can be required to remain in joint ownership indefinitely. A sibling may ask the court to end the co-ownership, which commonly leads to a judicial sale if no agreement can be reached.
- Question 3 What if one heir lives in the house for free?
- Answer 3 A judge may find that the heir has benefited from the property and order compensation to the others, sometimes by reducing that person’s share of the sale proceeds or treating the arrangement as unpaid rent.
- Question 4 Can we avoid court with a simple written agreement between siblings?
- Answer 4 Yes. A private written agreement can govern use of the house and how costs are divided. Having it reviewed or formalised by a notary gives it additional legal weight and may prevent future disputes.
- Question 5 Is it possible to renounce an inheritance that looks too risky?
- Answer 5 In many countries, you may refuse an inheritance or accept it “up to the amount of the assets”, limiting your personal exposure where the debts exceed the estate’s value. This requires a formal procedure, usually through a notary or court.
Comments
No comments yet. Be the first to comment!
Leave a Comment