
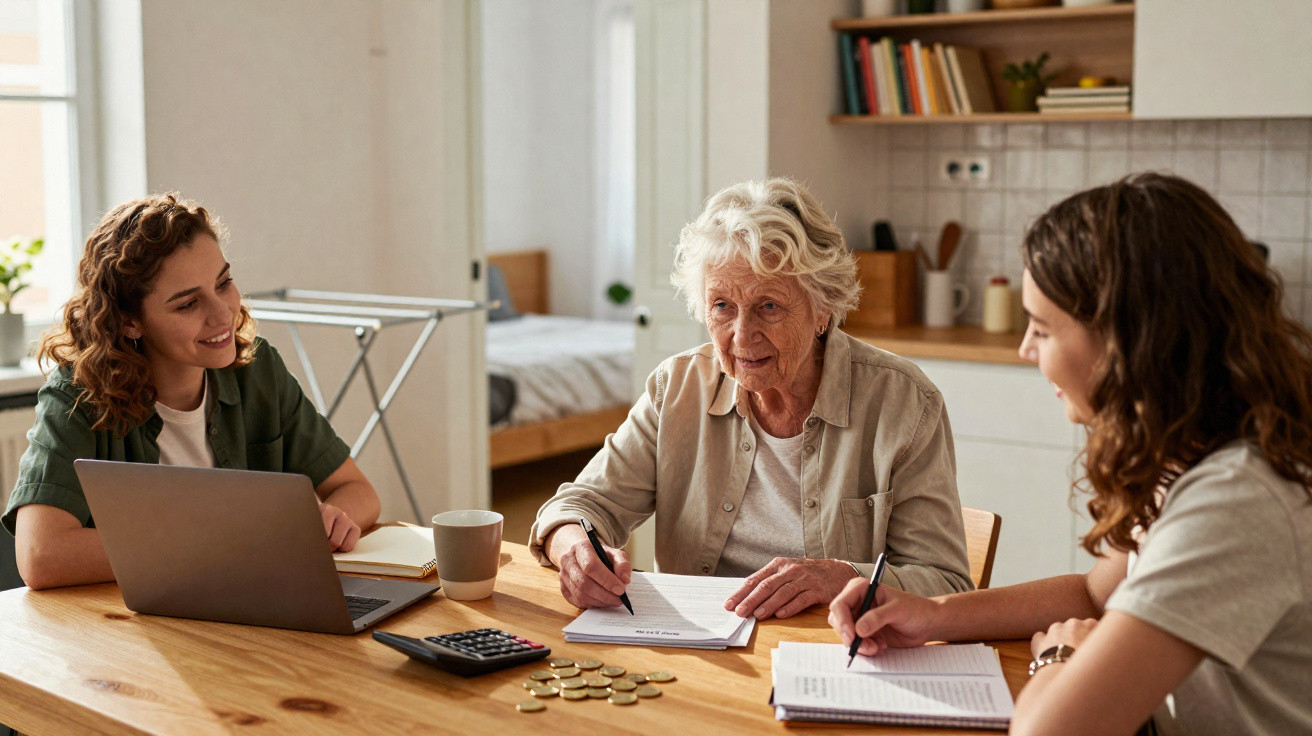
Her circumstances highlight the precarious position faced by many pensioners on modest incomes. Receiving €840 each month while paying a €1,200 housing bill, this woman in her eighties has had to reshape her day-to-day life. She now takes in two female students to help meet her outgoings and retain at least a small amount to live on.
When rent exceeds monthly income
On paper, the figures simply do not add up. This resident’s monthly income does not even cover her rent. She is already €360 short before buying food or paying for electricity, insurance, telephone bills and healthcare costs.
With an income of €840 and rent of €1,200, the budget is in deficit before everyday spending is even taken into account.
This may appear to be an unusual situation. Yet it reflects a very real problem for some older people, particularly in major cities and high-demand areas. Rents have risen over the years, while small pensions have not always increased at the same pace.
For this widow, housing has become the expense that determines every other part of her budget. Taking in two young women is not a social project or simply a way to make life more comfortable. It is a financial necessity.
Two rooms to stay afloat
Letting rooms provides an additional income stream. The money received can help pay rent, household bills or food costs. In her home, having two students living there materially changes the balance of the monthly budget.
This arrangement nevertheless requires careful organisation. Sharing a home means setting out private areas, house rules, timetables, and how the kitchen and bathroom will be used. For an older person, trust matters just as much as the amount paid.
- Put an agreement in writing, stating which room is available and the amount requested;
- Check that the accommodation meets decent housing standards;
- Review the tenancy agreement if the person is a tenant;
- Consider how the income received could affect certain benefits;
- Clearly specify which household bills are included in the amount charged.
A life shaped by a short contribution record
This pensioner says that she paid contributions for only eleven years. For part of her working life, she chose immediate income without appreciating the consequences this could have several decades later. That decision forms part of her personal history, but it also underlines the impact of short, interrupted or insufficiently declared careers.
A pension is built on periods of employment and income on which contributions were paid. Where years are missing, the final amount can be very low. Depending on the circumstances, periods of compensated unemployment, illness, maternity leave or child-rearing may sometimes generate entitlements.
The employment record should be checked
Checking an employment record before retirement, and even afterwards, makes it possible to verify the information held. A missing year, an employer not listed or quarters not recorded can reduce the value of a pension.
Particular attention should be paid to part-time work, seasonal jobs and short-term contracts. Some older files contain mistakes or incomplete details. It is not always possible to correct them, but checking ensures that an entitlement is not left unclaimed.
A short career cannot be corrected at 80, but the rights already earned must be examined carefully.
After a death, a couple’s entitlements do not always disappear
Bereavement can cause a sharp fall in living standards. When the deceased spouse provided a substantial share of the household income, the surviving person may have to manage alone in accommodation that has become too expensive.
In this context, a survivor’s pension is one option worth exploring. It represents part of the pension received, or which could have been received, by the deceased spouse. The rules vary between pension schemes. They may depend on age, family circumstances, financial resources or the length of the marriage.
This payment is not necessarily made automatically. An application must be submitted to the relevant bodies, together with several supporting documents. Delays in completing the formalities can temporarily leave someone without income they may need immediately.
Support that can reduce housing costs
Older people on low incomes can also look into housing assistance. The amount depends in particular on income, rent, location, household composition and the type of accommodation occupied. Housing two students may alter the claim, so any change should be reported to avoid a later repayment request.
The solidarity allowance for older people may also apply to some pensioners with limited means. Subject to conditions, it tops up income. Eligibility is based on an overall review of the person’s financial position, including investment income and money received from letting accommodation.
| Support to check | What it can provide |
|---|---|
| Housing assistance | A partial reduction in the burden of rent, depending on the circumstances |
| Survivor’s pension | A share of the entitlements earned by the deceased spouse |
| Solidarity allowance for older people | A top-up for people with limited resources |
| Local assistance | Occasional help with energy, meals or certain costs |
Disposable income, a warning indicator
Disposable income refers to the money left once fixed costs have been paid. It is used for food, healthcare, transport, clothing and unexpected expenses. In the case of this woman in her eighties, without letting two rooms, the amount would be negative as soon as the rent was paid.
When a budget becomes strained, cutbacks soon follow. Some people postpone a medical appointment, reduce their heating or cut back on food shopping. Such choices can further undermine health and independence.
Sharing a home can be a useful response, provided it is properly managed. A rented room generates income, but it can also reduce isolation. For the students, this arrangement may offer less expensive accommodation at a time when finding somewhere to live is becoming difficult. The balance remains precarious: it depends on the level of household costs, the stability of the occupants and the social security entitlements of the person providing the accommodation.
Comments
No comments yet. Be the first to comment!
Leave a Comment